
Social Security runs short by 2032: how retirees at every income level get hit
Trust fund depletion forces benefit cuts by 2032. Four households show the stakes.
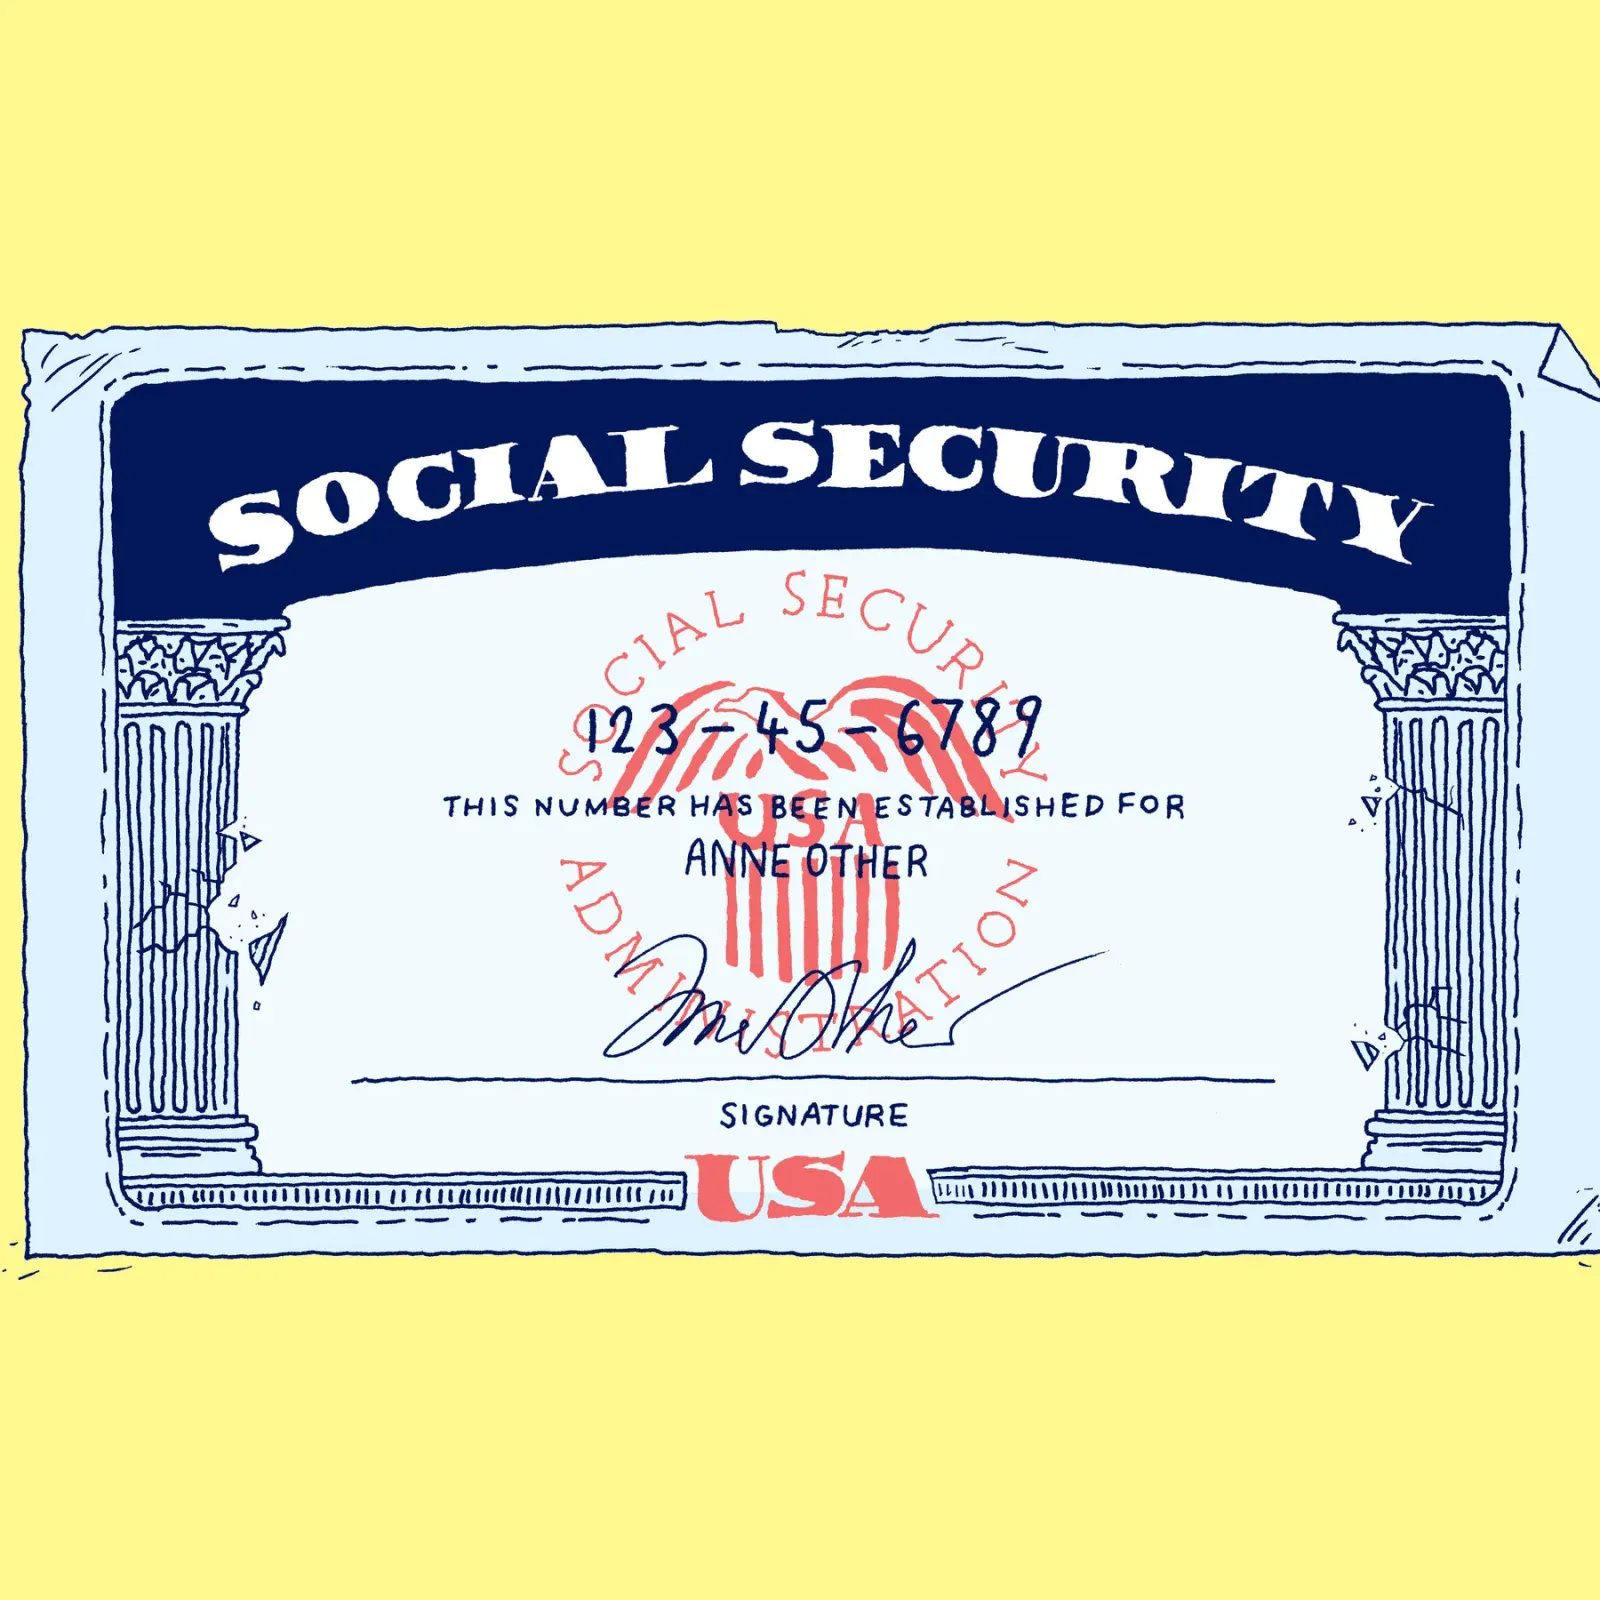
The Social Security trust fund is on track to run short by 2032, triggering automatic benefit reductions for retirees. Decision-makers should treat the program's projected shortfall as a planning trigger for retirement income strategies.
Social Security's trust funds are on track to run short by 2032, and when they do, benefits get cut automatically. That is the core finding of a New York Times analysis that models how four hypothetical households across the income spectrum would fare under the program's projected shortfall. The 'run short' moment is not a default or a bankruptcy; it is the point at which the program's reserves are exhausted, leaving incoming payroll taxes unable to cover full promised benefits. The result, as the Times puts it, is a reduction in benefits for every retiree in the system.
The Times' exercise is deliberately simple: four hypothetical households, each at a different income level, each relying on Social Security in retirement. The point is to show how the program's weight shifts as income rises. For lower-income retirees, Social Security is typically the primary source of income, often covering the majority of monthly expenses. For higher-income retirees, it becomes a supplement to pensions, 401(k)s, and savings. The 2032 trigger would hit all of them, but the pain would be most acute for those who have the least to fall back on.
The mechanics behind the shortfall are well understood. Social Security is funded by a payroll tax on current workers, and the surplus of those taxes has been building up in trust funds for decades. But as the baby boom generation retires and the ratio of workers to beneficiaries shrinks, the trust funds are projected to be depleted by 2032. At that point, the program does not go bankrupt; it simply pays out whatever current tax revenue allows, which is less than the full benefit formula. That is the 'reduction' the Times refers to.
The political dimension is where the story gets interesting. The 2032 deadline is not a distant abstraction; it is a fixed point on the calendar that forces a choice. Congress can raise payroll taxes, cut benefits, raise the retirement age, or means-test the program. Each option carries a political cost, which is why lawmakers have repeatedly deferred action. The Times' household-level framing makes the stakes concrete: every year of delay narrows the range of less painful fixes and increases the likelihood of an abrupt, across-the-board cut.
For executives and financial planners, the implications are immediate. Anyone designing retirement plans, pension strategies, or long-term savings guidance for employees needs to model a scenario in which Social Security pays out less than current projections. The Times' four households are hypothetical, but the underlying risk is real. A retiree who assumed Social Security would cover a certain baseline could face a shortfall precisely when they are least able to earn more income. For employers, that means stress-testing retirement readiness with a haircut to Social Security benefits, not just a straight-line projection. That is not a distant worry; it is a planning input that should be on every CFO's risk register today.
There is also a generational angle. Younger workers are paying into a system that may not deliver the same return their parents received. That perception, fair or not, shapes political attitudes and makes reform harder. If younger workers believe the system is broken, they are less likely to support tax increases to preserve it. This creates a self-reinforcing cycle: the more the program's solvency is questioned, the harder it is to build the consensus needed to fix it. The political economy of entitlement reform is notoriously difficult, but the 2032 date is a forcing function that will eventually break the logjam.
The bottom line for decision-makers is that the 2032 shortfall is not a hypothetical exercise. It is a scheduled event with a known trigger. The Times' analysis uses four households to make the point that Social Security is not a monolith; it is a lifeline for some and a safety net for others. The policy response will determine which of those groups bears the brunt of the reduction. For now, the only certainty is that the program as currently funded cannot keep its promises.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
Elon Musk unveils a flying car, and SpaceX helped build it
The Tesla CEO's showcase at a SpaceX facility signals a future where road and rocket engineering converge.
Apple's $2,000 iPhone Duo opens preorders, taking on Samsung and Google
Apple's first foldable hits the market at a premium price, reshaping a category Samsung and Google have led.

Pope Leo XIV, first American pope, diagnosed with lung cancer
The 71-year-old Chicago-born pontiff underwent successful surgery on his right lung, and his diagnosis raises new questions about his AI-focused papacy and the Vatican's future.