AI blow-up fears revive credit default swaps. Would they pay out?
The Economist asks whether CDS protection would actually cover an AI-driven debt crisis - and why the answer matters for CFOs and boards.

The Economist reports that credit default swaps are back in vogue as investors hedge against an AI-related debt disaster. For CFOs and risk officers, the critical question is whether these contracts would actually pay out in a systemic blow-up, not just a single default.
The Economist's finance desk is asking a question that should make every CFO with AI exposure pause: in an AI blow-up, would insurance actually pay out? The trigger is a quiet but telling shift in credit markets. Credit default swaps, the derivatives that act as insurance against corporate debt defaults, are back in vogue amid fears of a debt disaster tied to the artificial-intelligence boom. The revival is a warning sign that investors are no longer treating AI's massive capital spending as an unalloyed good. The article's framing is direct: the market is hedging against a scenario where the AI bubble bursts, and the insurance contracts meant to soften the blow may themselves be fragile.
For the uninitiated, a credit default swap is a contract in which one party buys protection against a borrower defaulting, and another party sells that protection for a premium. If the borrower defaults, the seller compensates the buyer. These instruments amplified the 2008 financial crisis, when sellers like AIG could not cover the claims. Now they are resurging, but the question is whether they will work as advertised when the stress is systemic rather than idiosyncratic. The Economist's question is not rhetorical; it points to a structural gap in how the market prices AI-related debt risk. The contracts are only as strong as the sellers behind them, and in a correlated downturn, many sellers would be hit at once.
The context is the AI debt pile. Companies from cloud providers to chipmakers have borrowed heavily to fund data centers, power infrastructure, and GPU fleets. The Economist's framing suggests that a blow-up could come from a sudden repricing of these assets, a wave of defaults among over-leveraged AI startups, or a broader tech downturn. In such a scenario, the demand for CDS protection would spike, but so would the risk that sellers cannot pay. Historically, CDS markets have been tested during periods of concentrated defaults, and the AI boom has created a uniquely correlated set of borrowers: many are dependent on the same few suppliers, the same energy sources, and the same investor sentiment.
The "would they pay out" problem is not hypothetical. CDS contracts are subject to basis risk: the protection may not perfectly match the underlying debt, especially for bespoke AI-related bonds. There is also counterparty risk, the risk that the seller of protection fails exactly when you need them. In a systemic event, many sellers would be hit simultaneously, and central clearing, while improved since 2008, does not eliminate the risk of a cascade. The Economist's analysis likely notes that in a true AI blow-up, the correlation of defaults would be high, and the insurance industry, along with banks and hedge funds that sell protection, could face claims that dwarf their capital. The question is not whether the contracts are legally valid, but whether the sellers have the liquidity to pay out in a crisis.
Regulators have pushed CDS trading toward central counterparties, which reduces bilateral counterparty risk but concentrates risk in the clearinghouses themselves. This is a double-edged sword: clearinghouses are better capitalized than individual dealers, but they are also the single point of failure in a systemic event. Post-2008 reforms required more collateral and margin, but they did not eliminate the fundamental mismatch between the notional value of protection sold and the liquid assets available to cover it. For AI-related debt, the problem is even more acute because the underlying assets are new, hard to value, and often tied to technology that could become obsolete quickly. The market is effectively asking whether the insurance industry can underwrite a risk that has no historical precedent.
For CFOs and risk officers, the takeaway is not to abandon CDS but to treat them as one tool among many. The protection is only as good as the seller's balance sheet, the collateral posted, and the legal certainty of the contract. In a fast-moving AI downturn, the market for CDS could become illiquid, making it hard to buy protection when you need it most, or to exit positions. The Economist's question is a reminder that insurance is not a guarantee; it is a promise that depends on the promisor's ability to pay. Companies that rely solely on CDS to hedge their AI exposure may find themselves exposed exactly when they thought they were protected.
The strategic stakes extend beyond the treasury. Boards should ask whether their companies' AI investments are hedged in a way that would survive a systemic shock. The revival of CDS is a signal that the market is starting to price in tail risks. For peers in similar roles, the lesson is to stress-test the insurance side of the balance sheet. What happens if your CDS counterparty is downgraded? What if the underlying AI debt is restructured in a way that triggers a credit event? The market is asking whether the insurance will pay out. The prudent answer is to assume it might not, and to plan accordingly. That means diversifying hedging tools, maintaining cash buffers, and understanding the specific terms of every protection contract. The Economist's question is a warning, and the smartest executives will treat it as a call to action.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
Anthropic's S-1 reveals $80.7B loss as it races OpenAI to IPO
The Claude maker files publicly for a Nasdaq listing under 'ANT,' exposing staggering losses and a world-altering ambition before it can beat OpenAI to the market.
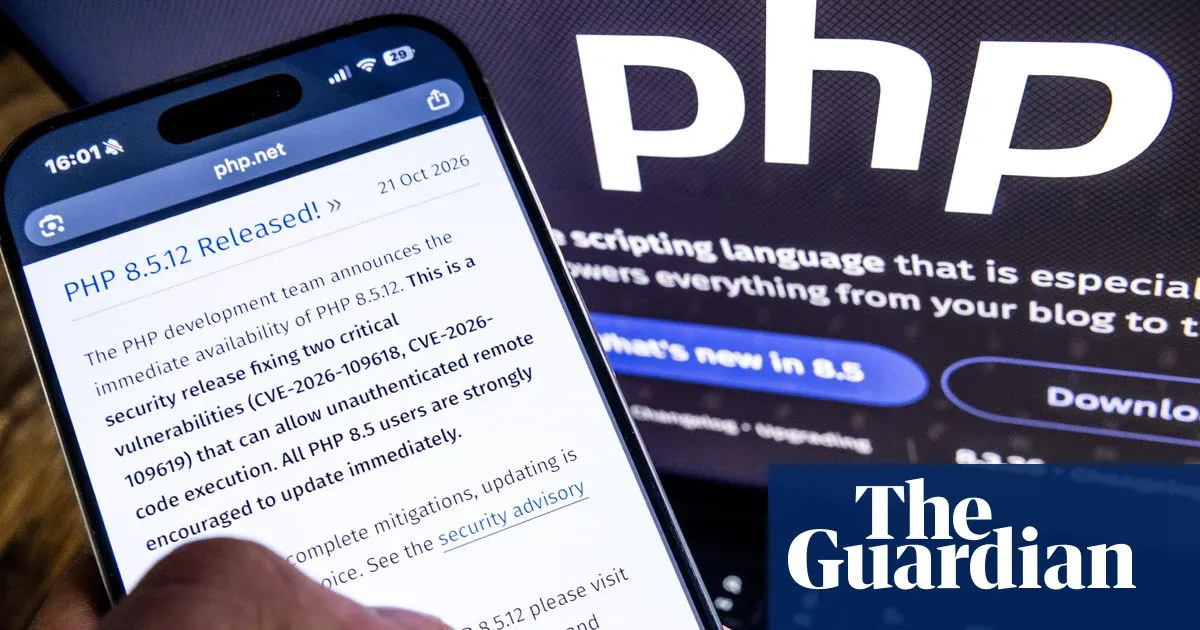
A flaw in PHP just forced governments to pull their own sites offline
European agencies from Belgium to Germany took websites dark to patch a critical weakness in the language behind almost 70% of the web, and the blast radius extends far beyond government portals.
BioWare shuts down, Mass Effect 5 dead after $55B EA buyout
The legendary RPG studio's closure lands months after a $55 billion investment group buyout of EA, raising tough questions for gaming's biggest acquirers.