Houthi Grip in Red Sea Raises Saudi Oil Export Risk
Tanker operators already knew the Red Sea was dangerous - now a Houthi foothold and a fresh pipeline strike put Saudi crude at even greater risk.
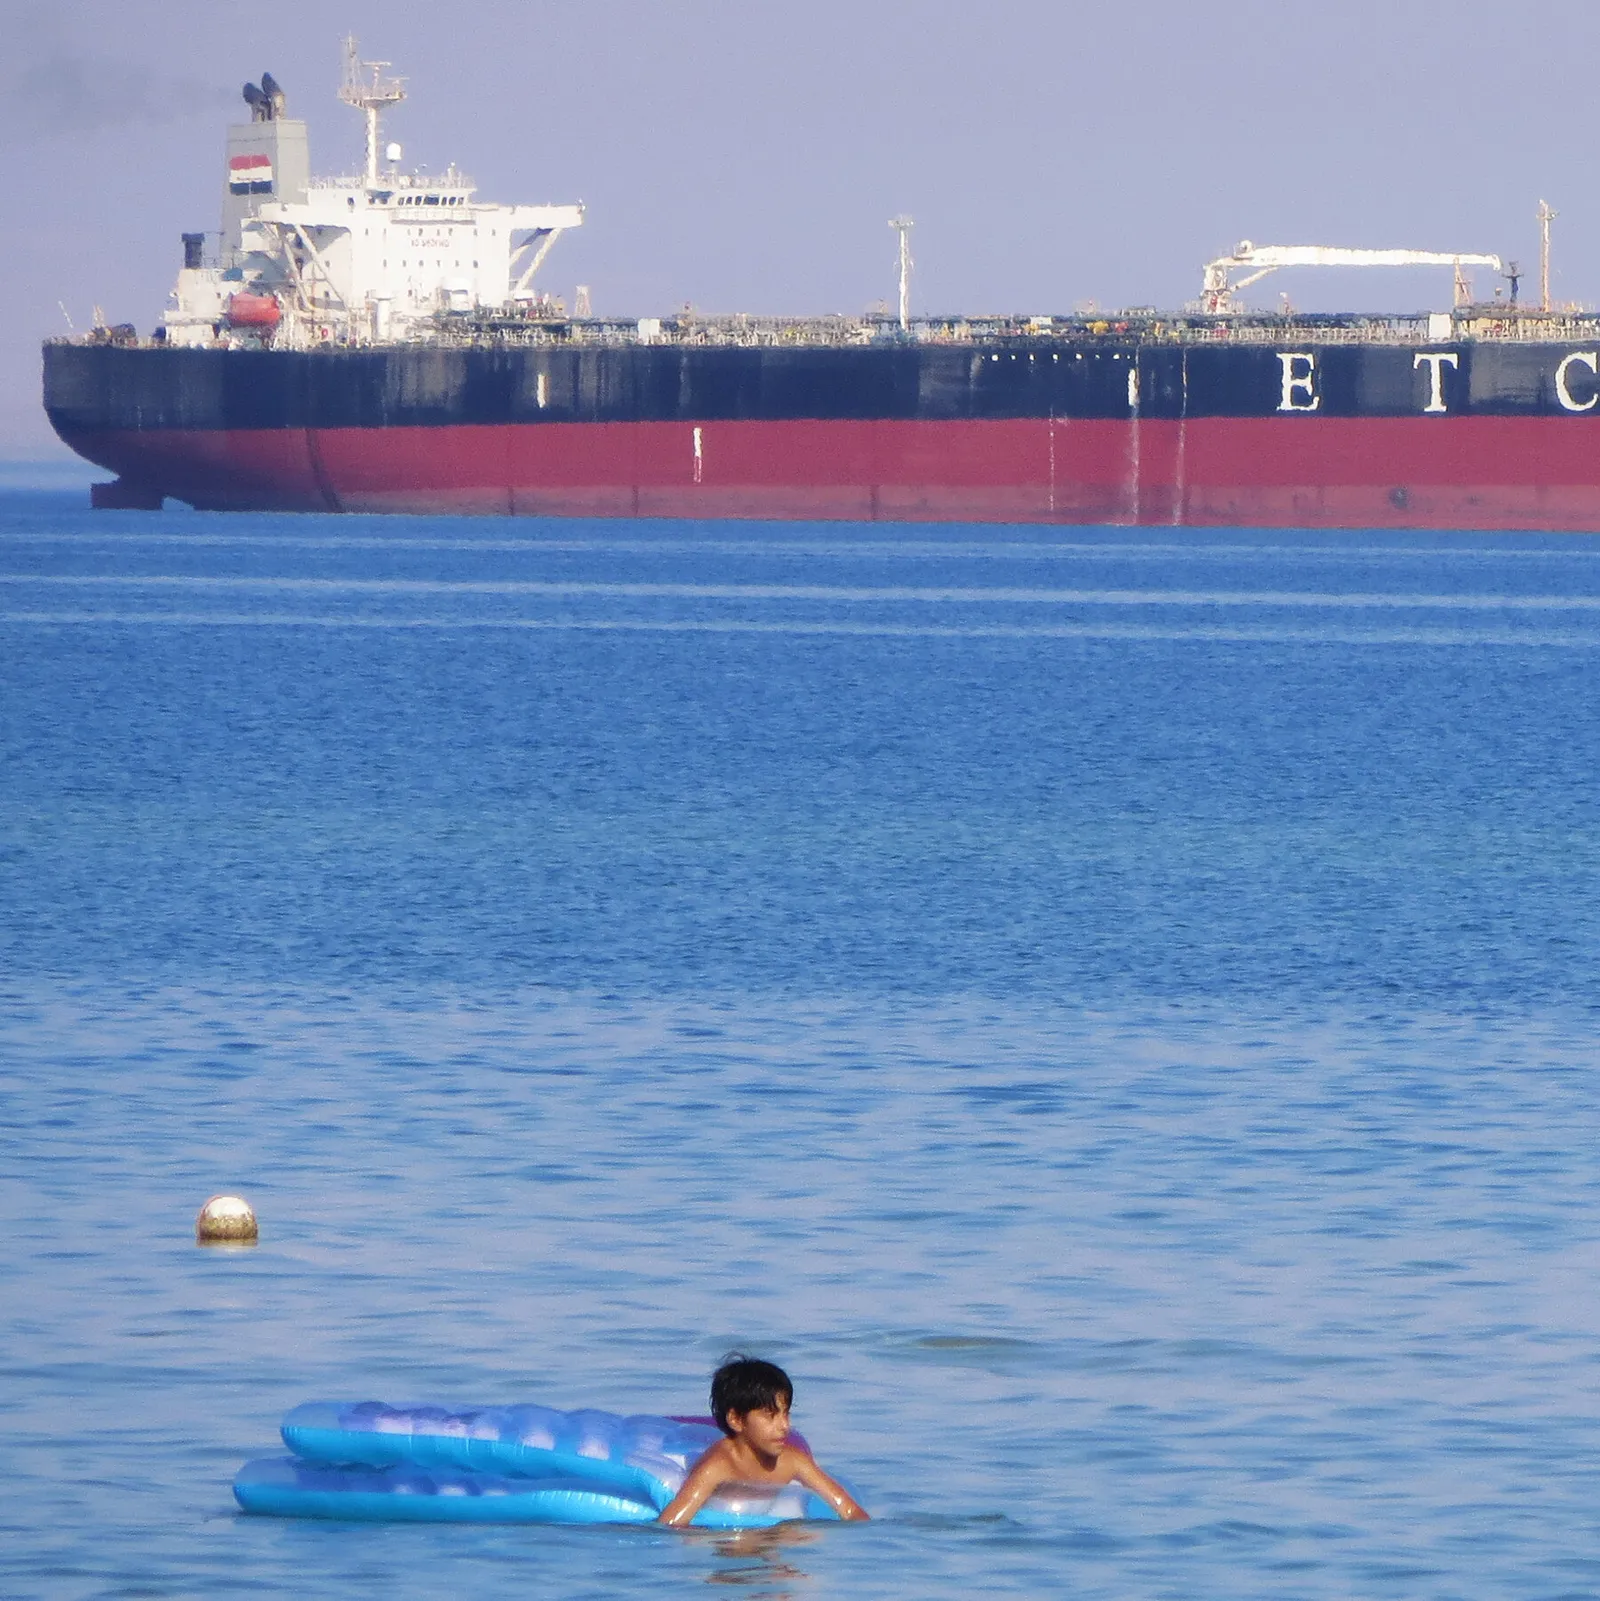
Ship operators face a more dangerous Red Sea as Houthi militias assert control after attacks on Saudi pipeline infrastructure. For energy and shipping executives, the corridor now carries a higher insurance premium and a louder alarm for routing and supply-chain decisions.
The Red Sea just became a more dangerous highway for Saudi oil, and the tankers carrying it are now sailing into a wider circle of risk. Ship operators already accepted severe danger in this region; they routinely navigated around piracy warnings, military standoffs, and the risk of being caught between an assault. But with Houthi militias now asserting control in the Red Sea, that baseline has moved higher. Adding a recent attack on a pipeline, the threat no longer stops at the sea itself. The infrastructure that feeds crude from Saudi fields toward the coast is now inside the range of attack, and that changes the math for anyone trying to move the kingdom's oil onto world markets. The New York Times reported the escalation in the bluntest terms: ship operators were already in a high-risk zone, and now the danger is greater again. For everyone who signs an underwater contract or clears a tanker for this route, that is a signal to rerun the models and reconnect the contingency list as if the Middle East energy route has been reassigned to a new danger class.
Why, it plays with when so much oil depends on a corridor that is actually just a tight body of water? The Red Sea leads to the Bab al-Mandab and then to the Suez Canal, a connection that draws European and Asian markets together through Middle East barrels. When a maritime hazard expanded here, the effects are immediate: insurers reprice war risk, vessel owners look for alternate stagings and then ask for premium freight, and energy traders add another gap in the futures they price as a safety after. In a normal chokepoint, a slight increase in danger is survivable. In the Red Sea, Houthi-era increase is not partial. It points at the fact that the route itself is vulnerable, and vulnerability makes producers nervous. For Saudi Arabia, whose margins and government budgets still depend heavily on crude sales, the Red Sea exposure is concentrated: an attack on a pipeline sits on an alongside the Strait of Hormuz lever, which together can cut the kingdom's ability to redirect its barrel.
Part of what makes this moment dangerous is that the Houthis use the coastline itself as a weapon. They do not need to send a full fleet to strike a tanker lane; they can coordinate from the shore, and their presence in the Red Sea narrows the navigable pass and forces vessels into the killing zone. In previous years, ship operators worked with a model that said: if you stay outside the corridor, you are safe. Now the corridor is more and more the center of a Houthi authority. As the militia extends control, moving a tanker through the Red Sea requires not just caution but also a decision on whether to be part of a route that has suddenly become a hostage path for insurance layers and for logistics.
For the oil market, the second-order effect is not just a premium on a charter. It is the risk that future crude flows take longer, c dropped, or have to travel around the Cape of Good Hope instead of the Suez shortcut. That type of change snaps global supply chains, because shorter routes release capacity in the shipping schedule; when the fast way is no longer always open, the fleet must hold extra days of transit and the worldwide pool of tonnage tightens up. The result is that European refineries with Saudi crude dependence and Asian buyers receiving Saudi barrels at the eastern end now all share the same concern. The reports of a Red Sea fatal with pipeline damage are not intended for storage: they affect the basis for what Saudi crude is producing, what it costs to freight, and what insurance means in every voyage that passes transit points.
(And for the strength of the policymakers in Riyadh, the region has a reputation for robust oil pipelines. The international market generally assumes that Saudi Arabia can push billion barrels from Saudi to the Red Sea without entering Hormuz. The exact fact that a pipeline attack puts this assumption in doubt is the biggest strategic break. Even if a crude tanker arrives safely, the cargo may never appear if the line feeding the western terminals is down; the is not just about vessels cruising through the sea, but about infrastructure triangulated on land. Executives who manage marine assets therefore need to expand the security conversation that began with the oil company and border protection agency.
The hard truth for boards and operators is that the Houthi claim is not a one-person standstill. It is a competitive scenario in which a militia controls the sea and its attacks on oil projects become more frequent when the fight escalates. For shipping executives, the next full risk review cannot stop at Suez. It needs to add a day-to-day map of Red Sea last mile, pipeline-to-terminal alerts, and insurance riders that could be just as expensive as the freight jump. For energy and capital teams, there is also a meadow to study: the pricing of Saudi crude and Saudi exporters may feel a long-term risk premium related to the route stability. In this capacity, the world is not just watching the Houthi take control of a strait, it is watching the change in what Saudi oil exports mean in the future.
For any operator active in the Middle East, the dose of this news is a direct call: do not wait for a formal government advisory to tell you how to treat this route. The shipping and cargo can be rerouted, the use of wider feeds shrank, and each voyage canned to be allowed extra time and extra cost. The worst case is now part of the everyday map, and the time to raise the residual risk is before, not after, the next tanker enters the area. The bottom line is that the Red Sea is not going to be the tranquil catch it was in the previous era. Saudi oil at all of the wells remains as valuable as ever, but getting it to the world just became a more strategic, exercised and expensive job.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
Royal Caribbean just spent $3B to own half of Sandals
The cruise giant is buying a 50% stake in the all-inclusive resort chain for $3 billion, a bet that land-based vacations are the next growth engine.
Paramount's Ellison: Merger Clearance Done, WBD Deal by Oct 1
David Ellison says the Paramount-WBD merger has full clearance after settling with state AGs, clearing the path for an October 1 close.
Paramount settles with 12 states, $110B Warner merger clears final hurdle
David Ellison's studio avoids a March trial and a $7M-a-day ticking fee by settling with state AGs over local job losses.