
Nvidia Is Historically Cheap, and the Huang Drama Is Why Buyers Won't Bite
MarketWatch's read on the AI bellwether is blunt: until the Jensen Huang uncertainty clears, a historically cheap multiple is a warning label, not a bargain.
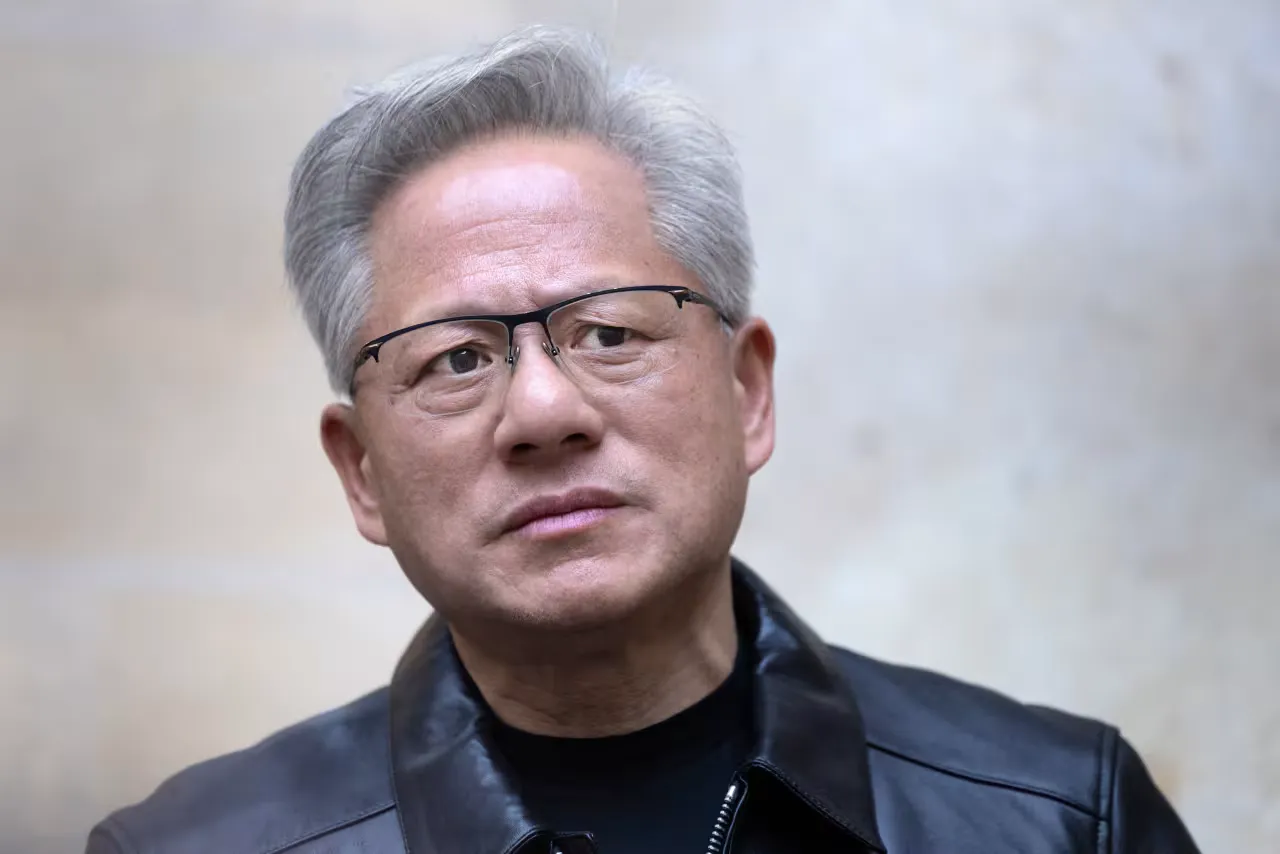
Nvidia is trading at a valuation MarketWatch describes as historically cheap, yet buyers are staying away because of unresolved uncertainty over how the drama surrounding chief executive Jensen Huang plays out. The consequence for decision-makers is that a depressed multiple on a key-person-dependent company is a risk signal rather than an entry point, and the same logic travels across AI-linked holdings.
Nvidia is trading at what MarketWatch calls a historically cheap valuation, and buyers are still refusing to step in. The reason is not a hidden accounting problem or a demand shock. It is the unresolved uncertainty over how the Jensen Huang drama plays out. The outlet's guidance to investors is unusually direct: do not try to pick a bottom in this stock, no matter how cheap it gets.
Read that twice, because it inverts the instinct most investors have been trained on. A stock that has sold off and now screens cheap is supposed to be the moment value hunters get excited. MarketWatch's argument is that this is precisely the wrong reflex here. When a single unresolved story is what is dragging a name down, the low multiple is not a discount. It is a placeholder for an answer nobody has yet. The market is not mispricing Nvidia out of carelessness. It is pricing in a question mark, and question marks do not clear on a schedule investors can trade around.
This is what key-person risk looks like when it shows up in a market capitalization. Nvidia's rise has been inseparable from Huang, its chief executive, whose public profile, technical roadmap and relationships with customers have been woven into the investment case for years. For most large companies, leadership noise is a footnote that gets priced in a day and forgotten in a week. For a company whose story is its leader, leadership noise becomes a valuation input. Boards at founder-led firms typically treat this as a governance exposure, and the market increasingly prices it the same way: not as a headline to ignore, but as a variable that widens the range of outcomes and raises the return investors demand to hold the stock.
There is a useful distinction between a stock that is cheap and a stock that is cheap for a reason. Screens are mechanical. They compare a price to earnings, sales or cash flow and flag whatever falls below a threshold, and that machinery has no way to price an open question. Historically, the names that look cheapest on those screens are often the ones the market has already decided carry risks the numbers do not capture. Value investors have a name for it: the value trap. The trap is not that the metric is wrong. It is that the metric is stale relative to the story, and the story is what moves the price from here.
So the practical case for waiting is about information, not courage. Buying a dip requires a thesis about what the price should be. Right now, per the source, the key variable is how the Huang situation resolves, and that variable is unknown. Until it resolves, a buyer is not underwriting Nvidia's business. They are underwriting the outcome of an open-ended situation they cannot model. The arithmetic that matters is simple: when the dominant driver of a stock's price is uncertainty, new information lowers risk without necessarily moving the entry price much. Patience is not a punt in that setup. It is the cheapest position available.
The stakes extend well beyond one ticker. Nvidia has sat at the center of the AI trade, and its valuation has functioned as a proxy for enthusiasm about the entire buildout. When the flagship name de-rates on non-fundamental uncertainty, hesitation tends to travel. Suppliers, partners and the broader complex of AI-linked companies typically see their own multiples questioned in sympathy, because the same investors own all of them and the same narrative supports all of them. That is the second-order risk for anyone with exposure across the sector. The question is rarely whether the leader's underlying business is intact. It is whether the market's willingness to pay a premium for the whole theme has quietly changed.
For executives and boards, the lesson is one of discipline. Separate the price from the story. A falling multiple is a data point, not a signal, and on its own it says nothing about whether the underlying business is winning or losing. What it does say is that the market has attached a discount to something it cannot yet see through. The professional move is to name that something explicitly, then decide honestly whether you have an edge in forecasting it. If you do not, the cheapness is not an invitation. It is a warning label.
None of this is an argument that Nvidia is broken. MarketWatch's point is narrower and harder to argue with: cheap is a description, not a catalyst. Until the Huang question has an answer, the buyers staying away are not being irrational. They are choosing to wait, and the source's position is that waiting is the right trade.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
GTA VI hauls $3.79bn in one day, out-earning every film ever made
Rockstar's own estimate covers a single Thursday plus a record 32.5m prerelease units, and it lands on every board weighing IP concentration, pricing power and launch risk.
FBI's crime database breached again, the second hack in months
CNN reports hackers hit the National Crime Information Center, the shared backbone of US policing, and the repeat timing is the part every security team should study.

S&P 500 Enters Correction, Down 10% From Its High on AI Worries
The index's slide past the 10 percent line is a symbolic verdict on investor mood, and the AI trade that powered the rally is now the thing testing it.