
Nvidia Shed $1 Trillion. Huang Has Five Ways to Force a Comeback.
The board said no, but a 3.5% stake, 200,000 petition signatures, and a $1 trillion market wipeout give Huang five levers to test it.
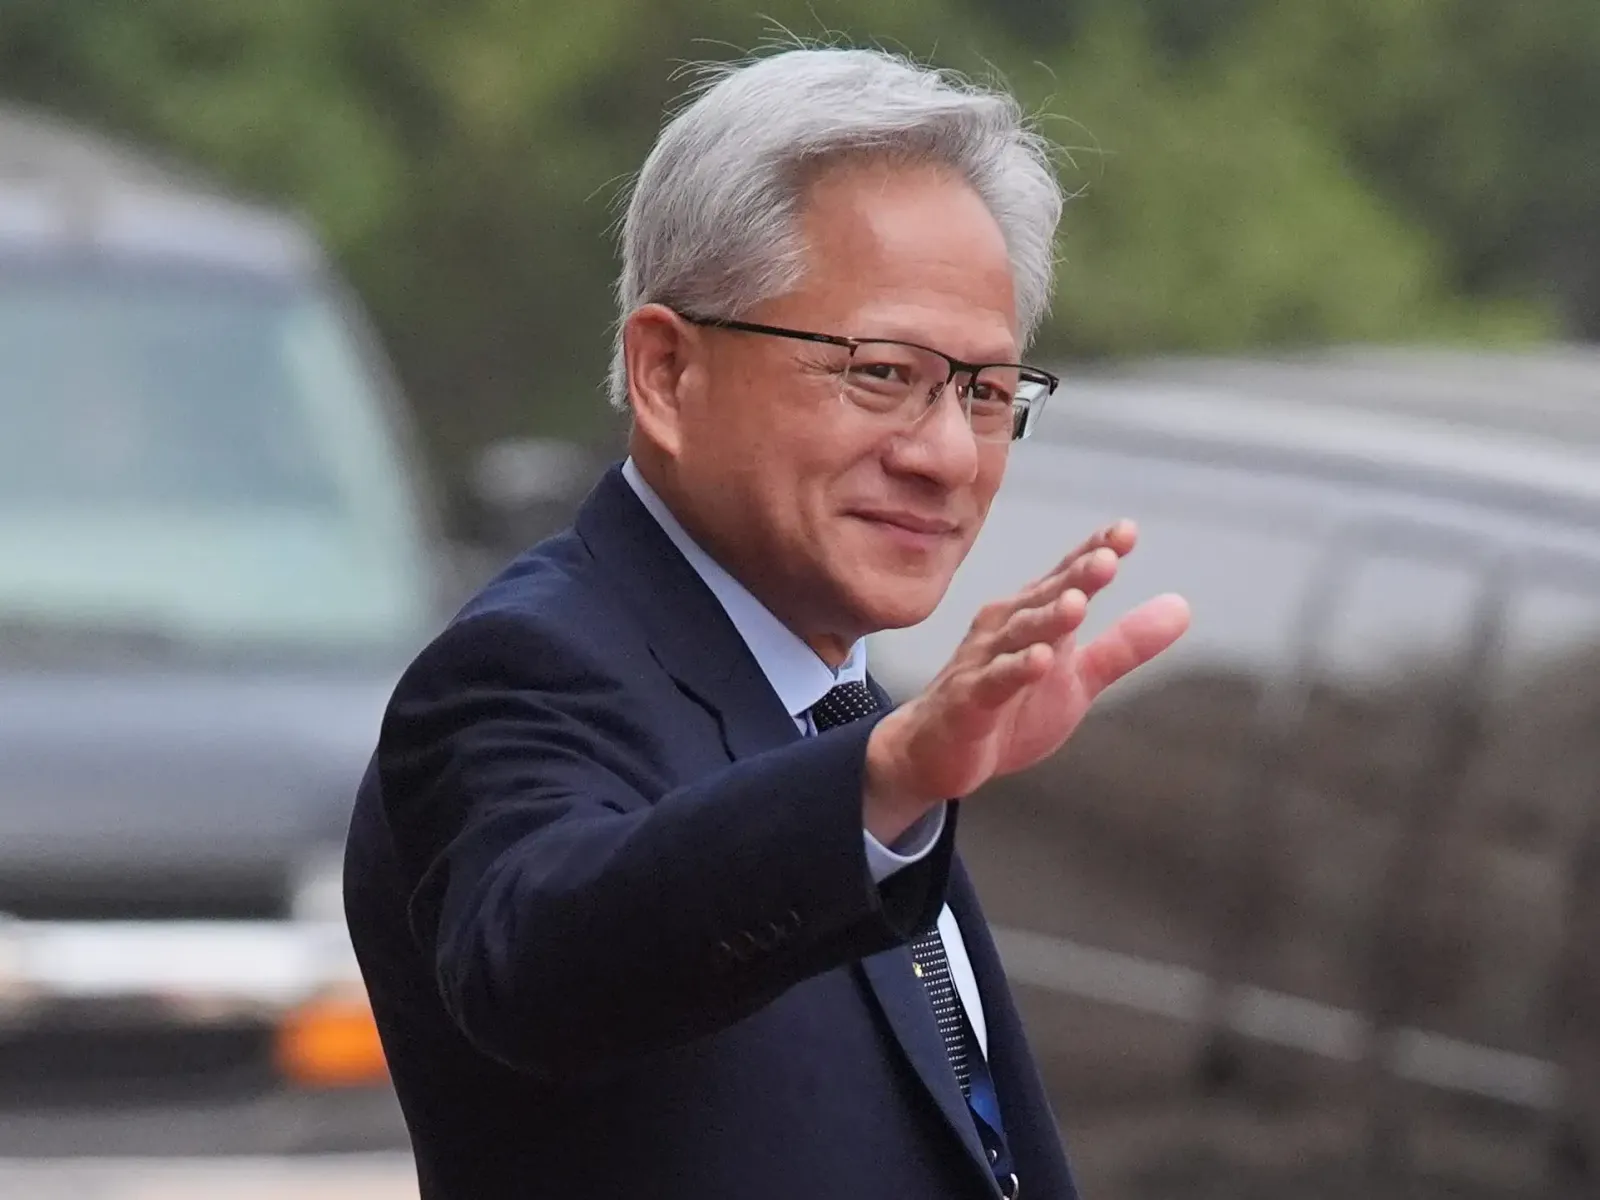
Jensen Huang, Nvidia's former CEO, says he would be "honored" to return, but the board has refused to reinstate him even as Nvidia has shed more than $1 trillion in market value and a reinstatement petition passed 200,000 signatures. Business Insider outlines five long-shot routes, from proxy access to a special meeting, that give boards and founders a live case study in how much power a founder's stake and brand still carry after an ouster.
Nvidia has shed more than $1 trillion in market value since Jensen Huang resigned as CEO, and the board has publicly thrown cold water on bringing him back. Huang has said he would be "honored" to return if the board decided it was in the company's best interest. The catch: only Nvidia's board can appoint its CEO, which makes persuasion the most straightforward route and the hardest one. The pressure is real, though. Semafor reported Wednesday that three Nvidia directors have pushed for Huang's return, and a petition calling for his reinstatement has topped 200,000 signatures.
Business Insider lays out five ways Huang could test that board and build shareholder pressure for a comeback: take his case directly to shareholders, turn the annual vote into a referendum on the board, put up two directors of his own, escalate to a full proxy fight, or force the issue at a special meeting. His roughly 3.5% stake and founding role are the fuel. Every route is a long shot, and the clock is not friendly.
Start with the softest lever. Huang does not need a formal vote to start rallying investors. Michael R. Levin, founder of shareholder-activism advisory firm The Activist Investor, said Huang could make the case now that he deserves to return and show the board that major shareholders agree. If enough investors signal they want him back, the board could act before the next annual meeting rather than risk a damaging public fight. Levin called that a "big if." "The board may take seriously that sentiment and act sooner, at least if they don't want a contested election in 2027," he said. That date matters. Nvidia's next annual meeting is likely in 2027, and Huang could use it to show shareholders have lost confidence in the board that accepted his resignation, urging votes against board nominees. His roughly 3.6% stake would not decide a vote alone, but it could matter in a close contest. In an uncontested election, Nvidia's proxy statement says a director who receives more "against" than "for" votes must offer to resign. The board has the final say, but a major public rebuke would sting. Levin's read: it would take "a huge effort and much luck," making the odds of a comeback "pretty remote."
Then there is the technical route. Nvidia's proxy-access rules let a qualifying shareholder place up to two independent director nominees on the company's own annual-meeting ballot. The bar is at least 3% of Nvidia's voting power held for three years. Nvidia's SEC filings show Huang has stayed above that threshold for more than three years, though the board would ultimately decide whether he met every technical condition. His nominees would still need shareholder backing, and Levin said two new directors would be unlikely to make much difference on their own because they would not alter the balance of power. Timing is tight: Nvidia has not set a 2027 meeting date, but its proxy materials indicate Huang would probably need to submit a proxy-access nomination between February 24 and March 26.
A full proxy fight is the louder version. Huang could recruit major Nvidia investors to elect a broader slate of directors more receptive to his return at the 2027 annual meeting. Unlike proxy access, he or allied shareholders would have to run and pay for their own campaign. Under the SEC's universal-proxy rules, a dissident shareholder must solicit proxies from holders of at least 67% of a company's voting power. That is a requirement to contact those investors, not proof that 67% would back his candidates. Nvidia's two largest disclosed institutional shareholders, BlackRock and Vanguard, held 7.43% and 7.31%, respectively, as of March 23. Whether either, or any other major investor, would support Huang's return is not publicly known.
The fastest formal route is a special meeting. Andrew Freedman, chair of Olshan's shareholder-activism practice, told Business Insider that Nvidia's bylaws allow shareholders, or a group, that has held 15% of its voting power for at least a year to demand one. Huang would need allies holding another 11.42% beyond his 3.58% stake. Freedman said the "cleanest" approach would be a two-step proxy campaign: first win enough support to call the meeting, then seek a vote to remove directors without cause. That second step would require support from at least two-thirds of all outstanding Nvidia voting shares under its Certificate of Incorporation. "If Huang or any investors want to strike now while the iron is hot," Freedman said, "they would do so through a special meeting."
There is a counterweight. Ann Lipton, a professor of law and the Laurence W. DeMuth Chair of Business Law at the University of Colorado Law School, pointed to the scrutiny Nvidia faces, including Huang testifying before Congress on December 1. "That might make it difficult for him to mount a challenge to the board at the same time," she said. In other words, the same public profile that makes him a credible rallying point also makes him a busy one.
Zoom out and the arithmetic is the story. Every formal path runs through allies Huang does not visibly have yet: 11.42% more for a special meeting, 67% contacted for a proxy fight, two-thirds of outstanding shares to remove directors. His stake is a megaphone, not a majority. For boards, the lesson is that a founder's brand does not leave when the title does, and succession fights can sit unresolved for years, with a 2027 annual meeting as the next hard deadline. For founders and CEOs watching, the playbook is worth studying either way: a shareholder base, a petition, and a public case can keep an ouster from ever being final. Nvidia's board said no. Huang has five ways to make it say yes, and none of them are quick.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
GTA VI hauls $3.79bn in one day, out-earning every film ever made
Rockstar's own estimate covers a single Thursday plus a record 32.5m prerelease units, and it lands on every board weighing IP concentration, pricing power and launch risk.
FBI's crime database breached again, the second hack in months
CNN reports hackers hit the National Crime Information Center, the shared backbone of US policing, and the repeat timing is the part every security team should study.

S&P 500 Enters Correction, Down 10% From Its High on AI Worries
The index's slide past the 10 percent line is a symbolic verdict on investor mood, and the AI trade that powered the rally is now the thing testing it.