
Gamified payments convert Gen-Z men and women at nearly identical rates
Research in the International Journal of Business Information Systems finds gamified mobile payment features may lift adoption in emerging economies, and the gender gap fintech marketers budget around barely shows up.

New research published in the International Journal of Business Information Systems finds that gamified features in mobile payment applications may significantly increase adoption among consumers in emerging economies, with men and women responding in almost identical ways. For operators and investors, that undercuts gender-based segmentation as a growth lever and shifts the competitive question to reward mechanics, retention, and cost per acquired user.
The gender gap that consumer fintech teams build campaigns around did not show up in the data. Research published in the International Journal of Business Information Systems finds that gamified features in mobile payment applications may significantly increase adoption among consumers in emerging economies, and that men and women responded in almost identical ways. That second finding is the one worth circling. The study's headline claim is about adoption; its more commercially explosive claim is about parity. If a points streak, a badge, or a leaderboard moves a 22-year-old man in one emerging market and a 22-year-old woman in another by roughly the same amount, then a large slice of the standard fintech growth playbook, which splits creative, channels, and product hooks by gender, is solving a problem that may not exist.
Start with what the research actually says, because the hedging matters. The finding is framed as "may significantly increase adoption," language that signals modeled or survey-based evidence rather than a live, at-scale deployment. It covers consumers in emerging economies, not mature card markets. And it is published in an academic journal, which means it arrives as a hypothesis to test, not a mandate to rebuild a product roadmap on Monday. What it does do is hand operators a cheap, testable lever at exactly the moment when customer acquisition costs in digital payments have become the binding constraint on growth in most phone-first markets.
"Gamified features" is a broad tent. In practice it typically means streaks that reward consecutive days of use, points and badges that mark milestones, leaderboards that make sending or spending social, referral loops that pay users for bringing in friends, and challenge mechanics that turn a routine bill payment into a small win. None of that is new. What is new is where it is being pointed. In markets where cash still dominates everyday transactions, the barrier to a mobile wallet is rarely the technology; it is trust, familiarity, and the nagging sense that money on a phone is money you cannot see. Gamification attacks that directly. It makes an unfamiliar interface feel like a game the user already knows how to play, and it gives them a reason to open the app on a Tuesday when they have nothing to pay.
Context matters here. Mobile wallets have spent more than a decade becoming core infrastructure in parts of Africa and South Asia, where bank branches are sparse and phone penetration ran ahead of card networks. That build-out created the rails. What it did not create, in most cases, is habitual daily engagement. A wallet used once a month to receive a remittance is a utility; a wallet used four times a week is a platform, and platforms are where lending, insurance, and merchant payments get sold. That is why adoption is not a vanity metric. It is the gate to every higher-margin product a payments company wants to layer on top.
The caveats deserve equal billing. Gamification is not free, and it is not permanent. Rewards that pull users in can also train them to expect a payout for behavior they would eventually do anyway, and the moment the incentive is withdrawn, the habit can evaporate with it. There is a design risk too: mechanics that feel extractive, that push users toward spending they did not plan, or that dress up fees as prizes tend to generate backlash faster in tight-knit communities than in anonymous ones. And in most markets, rewards, referrals, and anything resembling a lottery sit close to consumer protection rules, data privacy regimes, and know-your-customer obligations. None of that kills the strategy. It just means compliance and product need to be in the room before the growth team ships.
The parity finding carries a second-order consequence that is easy to miss. If men and women respond the same way, then gender is not a useful segmentation variable for this product category, and differentiation has to come from somewhere else: the quality of the mechanics, the speed of iteration, and the economics of the reward. That is a harder competition than a media-buying contest. It rewards teams that can run tight experiments, kill losing mechanics quickly, and hold reward costs per retained user below the lifetime value they unlock. For investors underwriting emerging-market fintech, the relevant question shifts from "how big is the addressable market" to "what does it cost to make a wallet habitual, and does gamification lower that number."
What to watch next is whether the effect survives contact with reality. Academic findings on adoption intent are a starting gun, not a finish line; the proof shows up in twelve-month retention curves and in what happens when the streak breaks. Watch, too, for incumbents. Banks and telecom operators with existing distribution can copy a points system in a quarter, which means any advantage from gamification is likely to be temporary and execution-based rather than structural. The board-level question is blunt: if the gender gap in your growth model is not real, what is your actual moat, and how fast can you build it before someone else does?
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Science
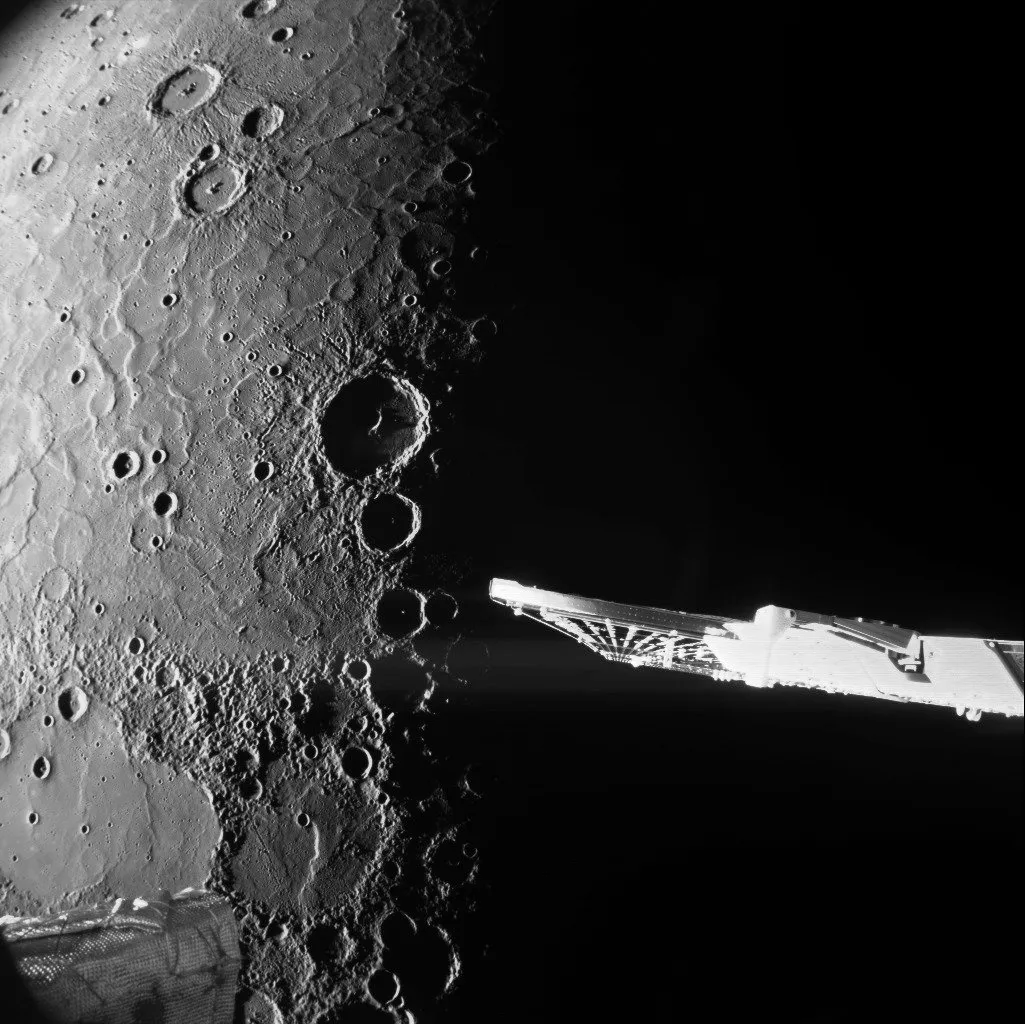
Europe and Japan park $2B twin probes at Mercury after eight years
BepiColombo's arrival ends an eight-year, $2 billion cruise and hands Europe and Japan a multi-year data edge on the solar system's least-studied planet.
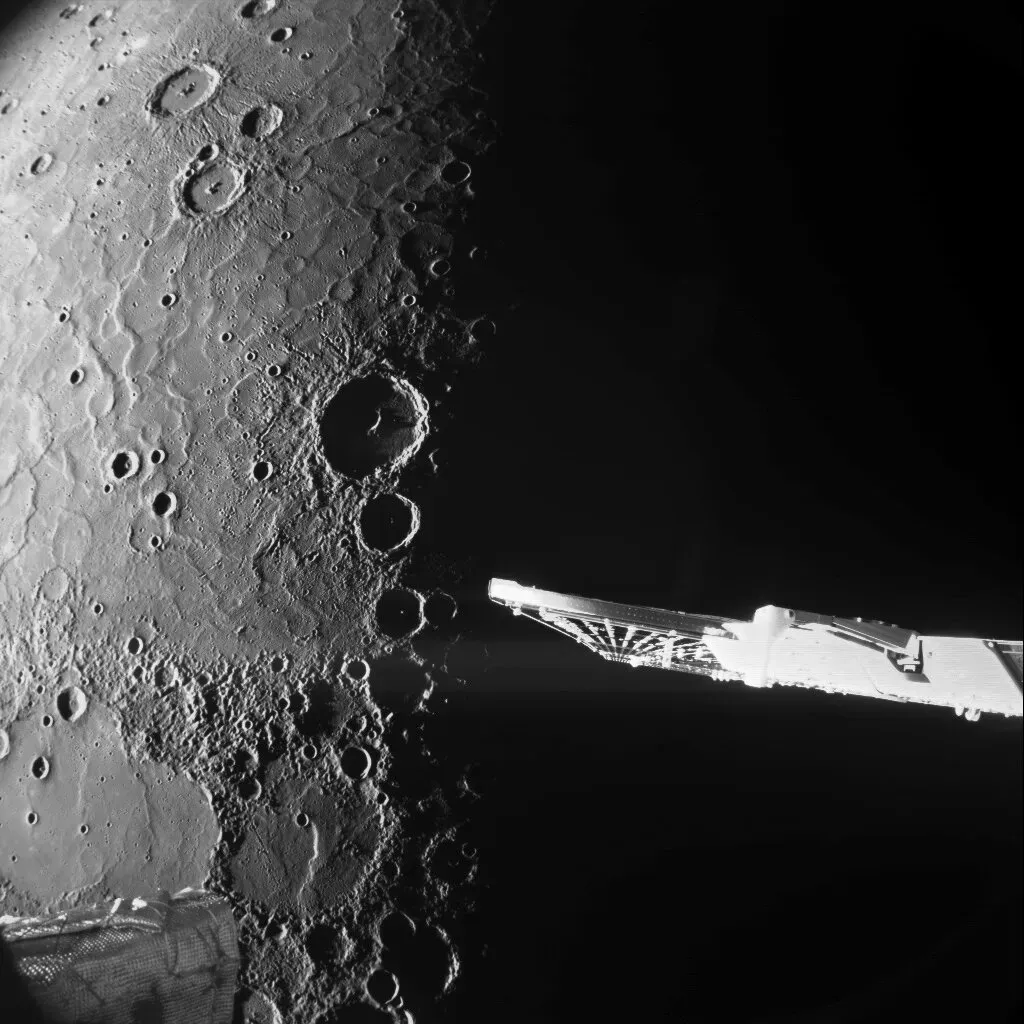
BepiColombo becomes only the second spacecraft ever to orbit Mercury
The international mission reaches the planet closest to the sun, giving scientists a rare second set of eyes and giving operators a case study in long-horizon R&D.
COP31 stalls as countries weigh forcing a Saudi showdown on fossil fuels
Two weeks of UN climate talks in Turkey have overrun without a deal, and the decision now facing governments will shape energy costs, transition timelines and capital allocation for years.