
Investors Are Giving Up on China as Stocks Hit Lows
The Hill reports Chinese equities are at lows for two fundamental reasons, a signal that the selloff is about more than sentiment.
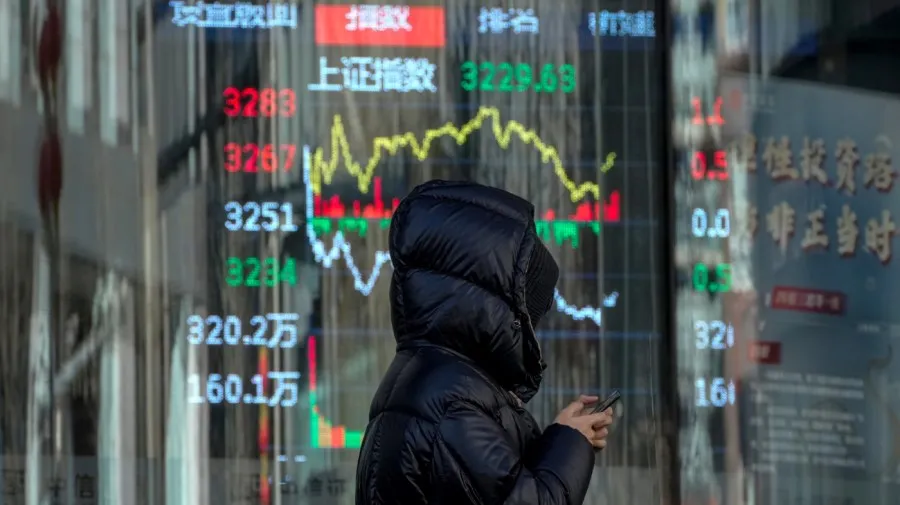
The Hill reports stock investors are giving up on China as Chinese stocks hit lows for two fundamental reasons. For decision-makers, the shift matters because it can reshape global capital flows, emerging-market allocations, and China-exposed fundraising.
The Hill reports that stock investors are giving up on China, and Chinese stocks are hitting lows for two fundamental reasons. That is the whole story in one line, but the phrase "giving up" does a lot of work. It is not "getting cautious." It is not "taking profits." It is not "waiting for a better entry point." Giving up means the investment case itself is being marked down, and capital is being reallocated away. For anyone with China exposure, that is a different problem than a normal selloff.
The source says the reasons are fundamental. In markets, that word is a signal. Technical reasons are flows, positioning, momentum, and sentiment. Fundamental reasons are earnings, growth, policy, governance, debt, and demographics. When investors cite fundamentals, they are saying the problem will not be fixed by a bounce. The Hill's summary does not name the two reasons, but the framing tells you the selloff is not a trading blip. It is a verdict on the underlying assets. That is why the word fundamental matters more than the word low.
For context, China's equity market is not one thing. It includes onshore A-shares traded in Shanghai and Shenzhen, offshore H-shares in Hong Kong, and US-listed ADRs. Foreign investors typically access these through Stock Connect, qualified foreign institutional investor programs, and exchange-traded funds. When global allocators give up, they often cut across all of those vehicles. That can hit valuations, liquidity, and the IPO window at the same time. For founders and CFOs, a closed equity window means fundraising gets harder, private capital becomes more important, and listing elsewhere starts to look less like a choice and more like a necessity.
Why does this matter beyond China? Because China is a major weight in emerging-market indices. If global investors reduce China, they do not just hold cash. They redeploy. That capital can flow to India, Japan, Southeast Asia, Latin America, or developed markets. The result is a relative valuation shift. Markets that were once cheap because they were ignored can re-rate. Markets that depended on China growth can de-rate. The Hill's report is a data point in that rotation. It says the marginal buyer of Chinese equities is not just absent. The marginal buyer is leaving. For allocators, the question is not whether China is cheap. The question is whether cheap is enough.
The second-order effects run through private markets. Public comparables set the tone for private valuations. If Chinese public equities stay at lows, private marks follow. Exit routes narrow. A US IPO for a China-based company is already a complicated path. Hong Kong has its own liquidity challenges. Strategic buyers may still step in, but they can dictate terms. For boards, this is not an abstract macro call. It is a direct input into dilution, down rounds, and governance terms. It also affects supply chains, joint ventures, and data compliance, because capital and operations are linked.
Policy response is the wild card. Historically, Chinese authorities have used tools to stabilize markets, including state fund buying, monetary easing, and regulatory signals. Those tools can produce sharp rallies. But if investors are giving up for fundamental reasons, policy can change the price without changing the case. That is the trap for executives. A policy bounce can look like a turn. It can pull in fast money. It can create a window to raise capital. But it may not restore the long-term buyer. The source does not mention policy, but this is how markets typically behave when sentiment and fundamentals diverge.
The strategic stakes are clear for CEOs, CFOs, and boards. If you have China revenue, China supply chain exposure, or China-based investors, you need scenario planning. Ask what happens if China is no longer a growth premium. Ask what happens if it becomes a value trap. Ask what happens if global capital stays out for years, not quarters. The Hill's report is not a prediction. It is a signal that the investors who once provided liquidity, expertise, and patience are walking away. When they walk, they take all three. That changes the game for everyone left at the table.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Politics
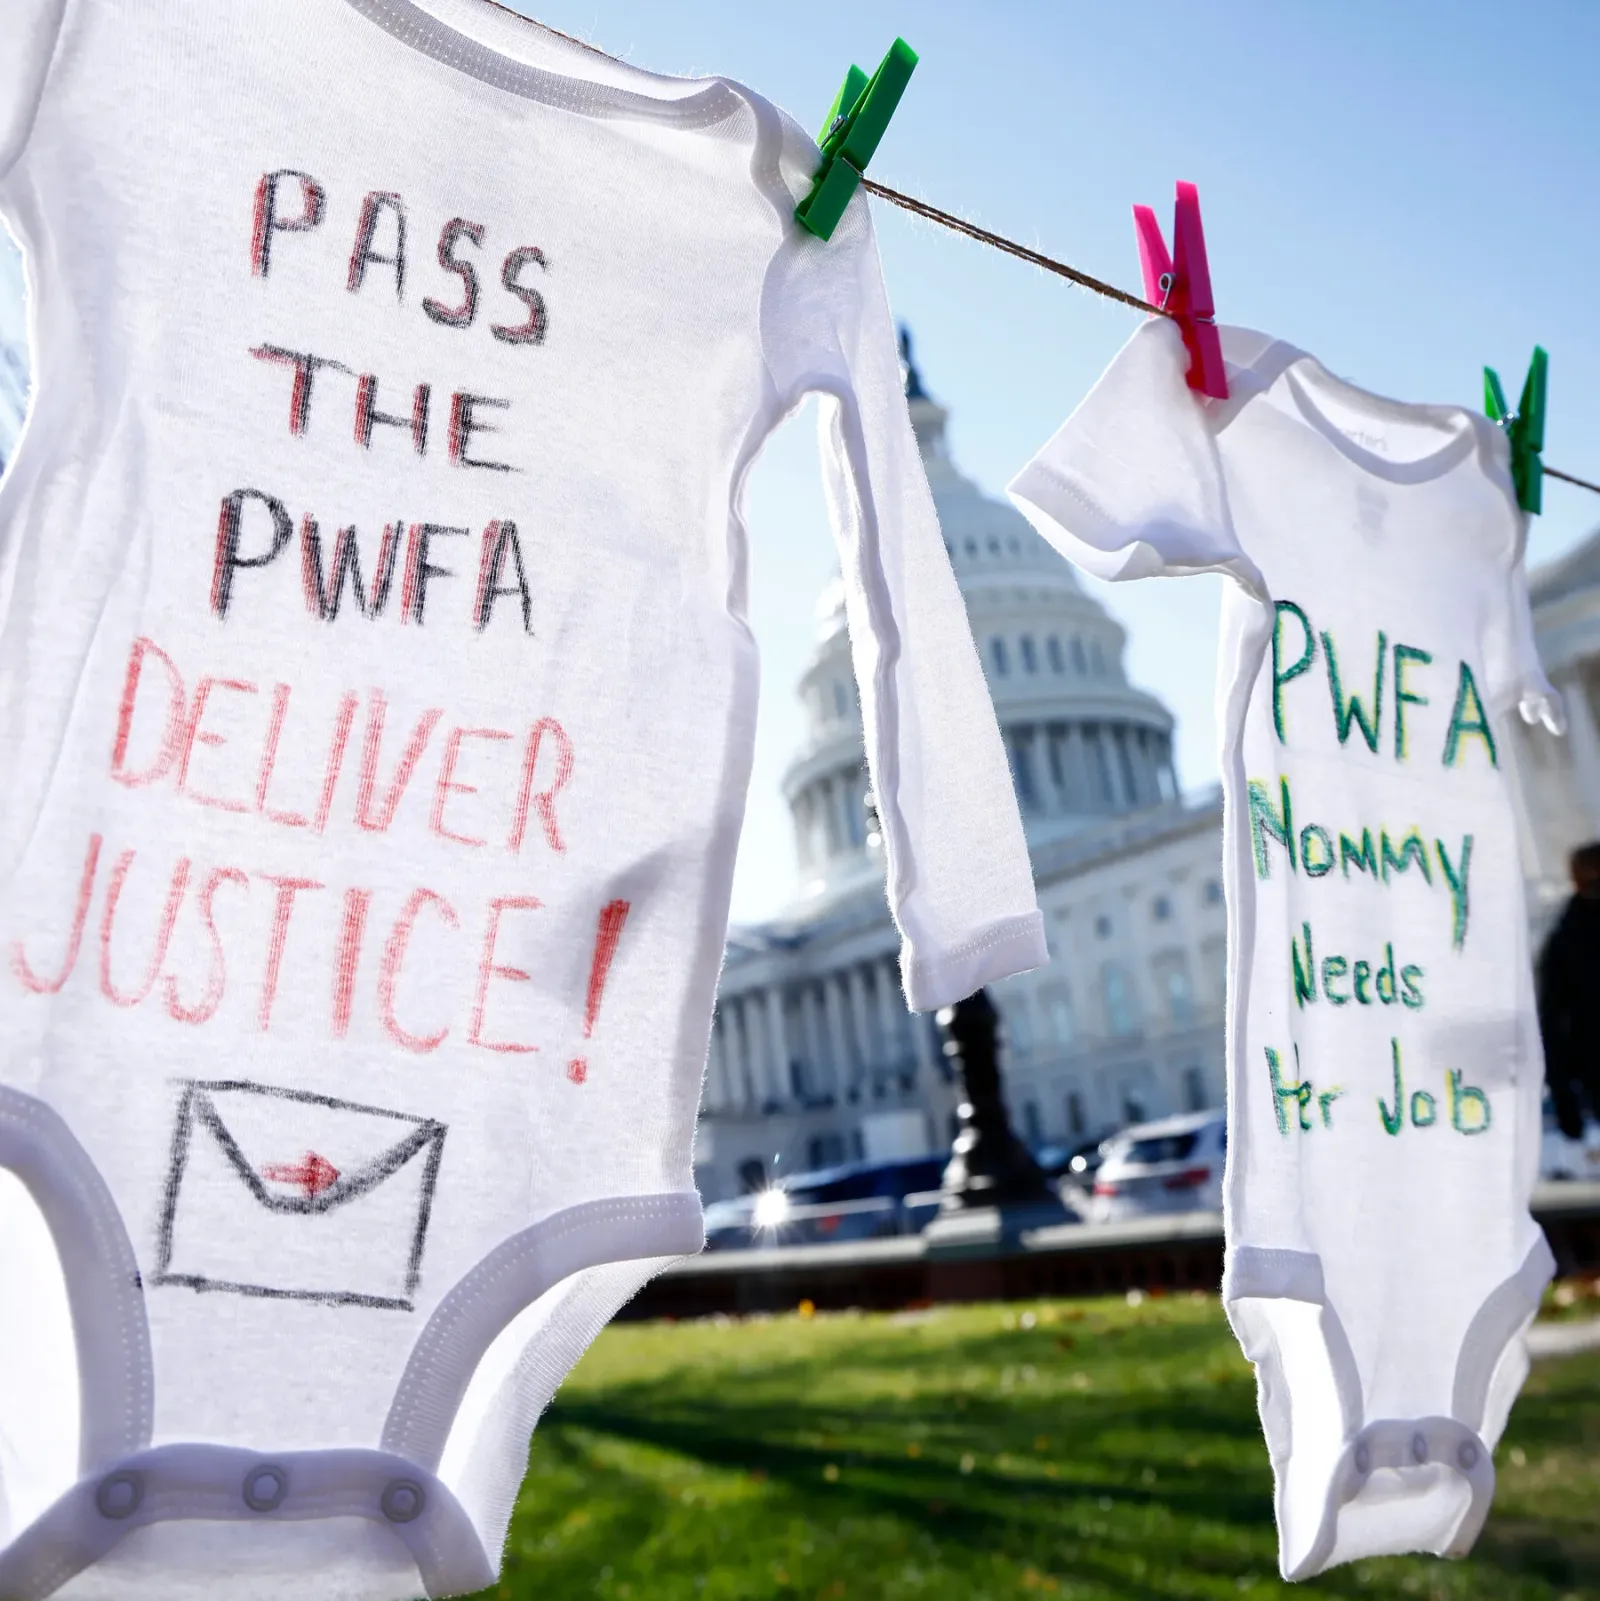
Fifth Circuit Kills Pregnant Workers' Law Over Pandemic Proxy Votes
A procedural ruling, not a policy one, has blocked a federal pregnancy-accommodation law and put every pandemic-era statute in the crosshairs ahead of an expected Supreme Court appeal.
Measles kills a Virginia child under 5, the state's first death of 2026
Virginia's health department confirmed the death but withheld the child's vaccination status, leaving schools, clinics and employers to plan around the one detail that would explain the most.
Former Brazilian President Bolsonaro Hospitalized with Intestinal Obstruction
The health status of the former far-right leader raises immediate questions about political stability and the trajectory of Brazil's conservative movement.