
Polymarket CEO calls Trump Jr. tie 'overblown' as prediction markets chase legitimacy
Shayne Coplan used the DealBook Summit to shrink the story of a Trump-family-linked investor in his prediction market, a bet that optics can be managed before regulators and partners do the math.
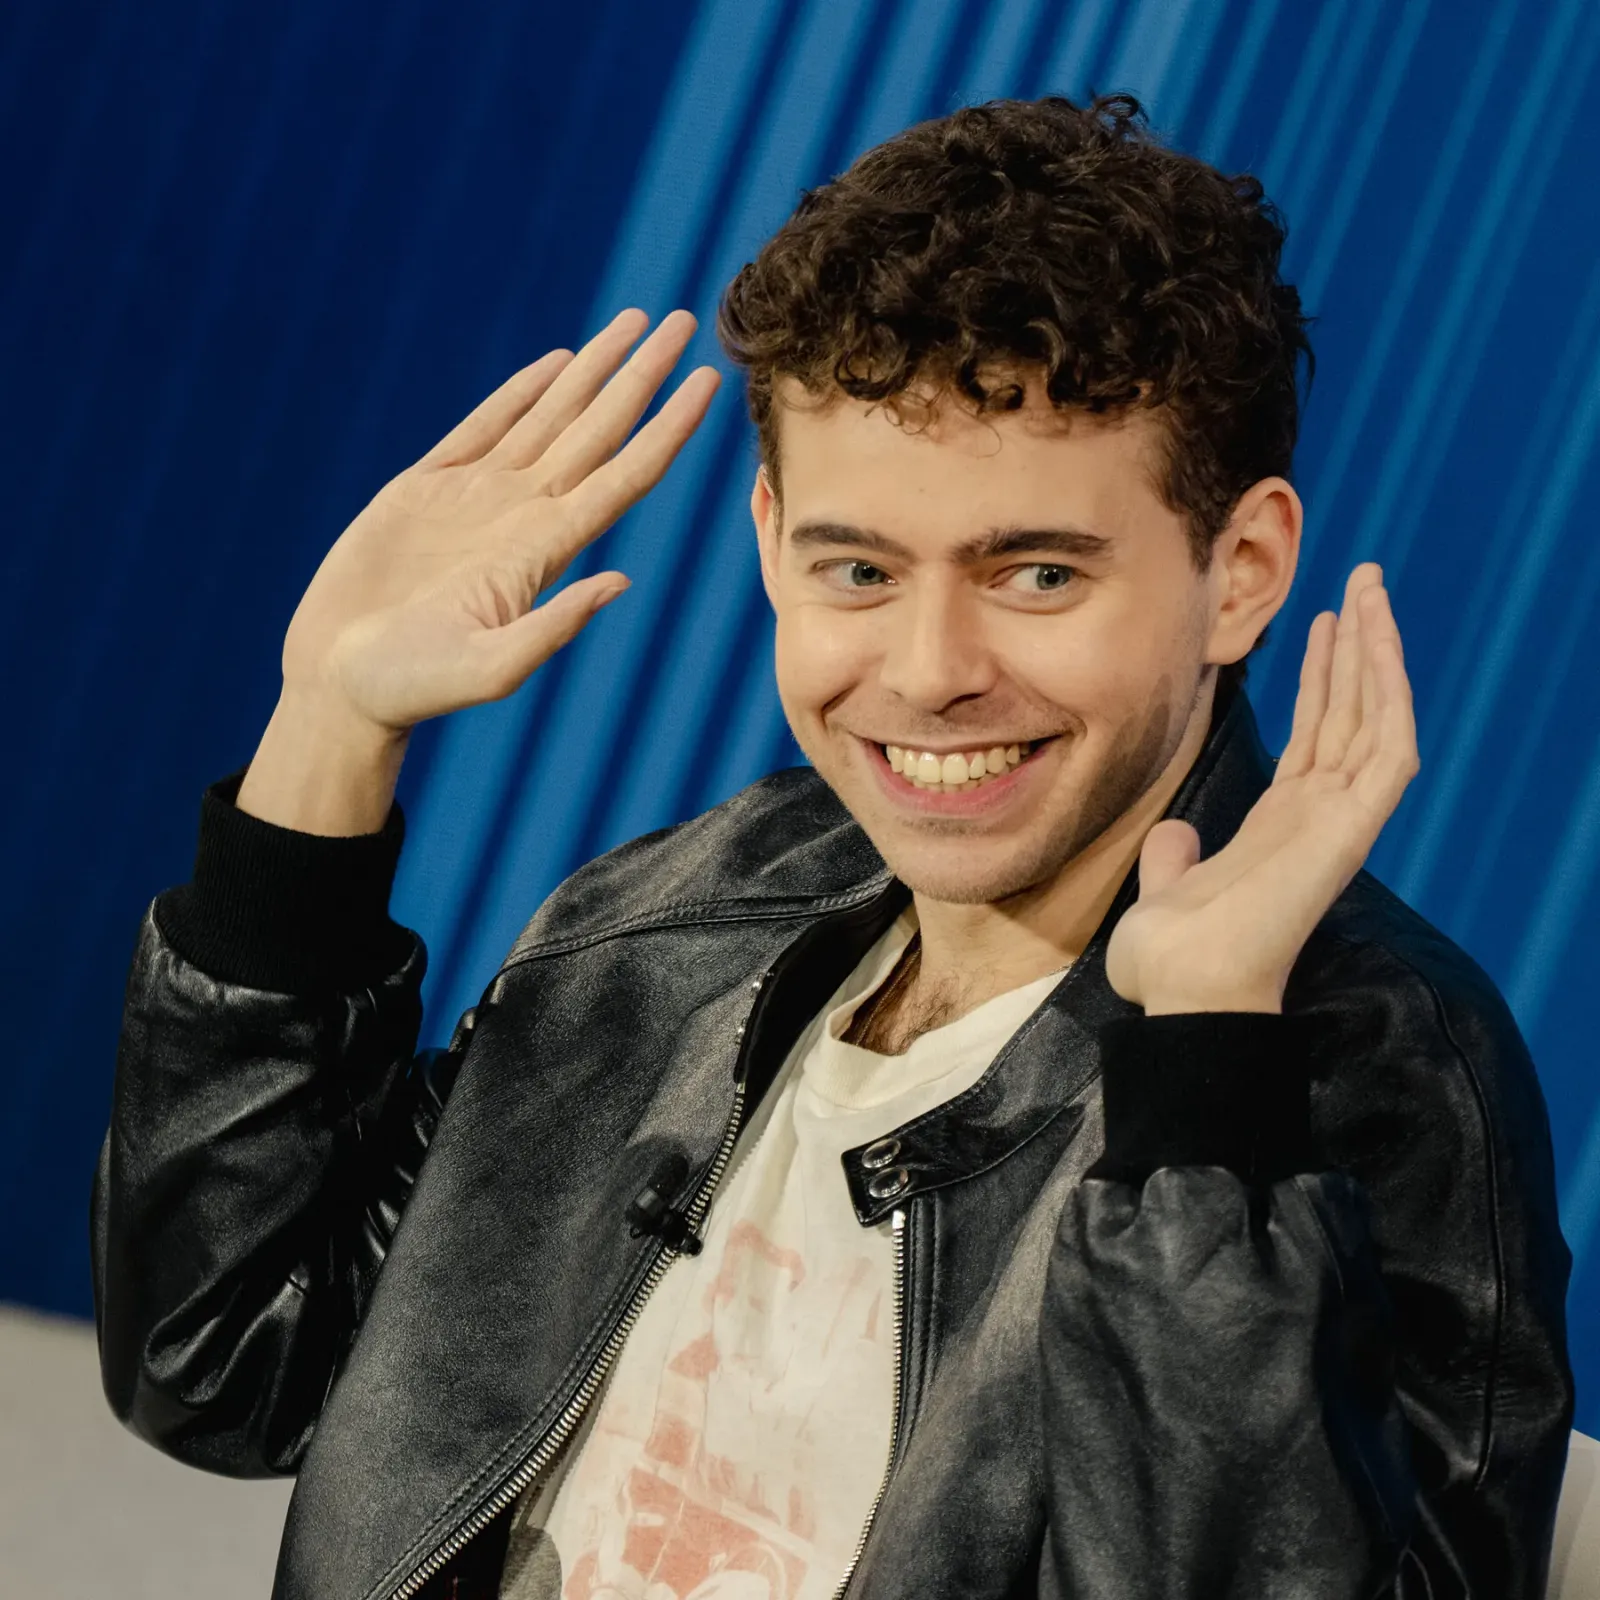
Polymarket founder Shayne Coplan defended the investment in his company by a firm associated with President Trump's oldest son, Donald Trump Jr., telling the DealBook Summit that the involvement is 'overblown.' For executives, the exchange is a case study in how politically connected capital creates a disclosure and credibility burden that outlasts the check itself.
Polymarket founder Shayne Coplan walked onto the DealBook Summit stage and did the thing founders rarely do when a politically charged investor sits on the cap table: he played it down. Coplan defended the investment in his company by a firm associated with President Trump's oldest son, Donald Trump Jr., and described that involvement as 'overblown.' He did not treat it as a governance question, a regulatory risk, or a conflict-of-interest headline. He treated it as noise. Whether it stays noise is now one of the more consequential open questions in the prediction-market business, because the industry's next chapter depends less on how many users trade contracts than on whether Washington, Wall Street, and the press decide the product is legitimate.
Start with what Polymarket actually is. It is a prediction market: users buy and sell contracts tied to the outcome of real-world events, from elections to economic data to sports, and the price of each contract functions as a live, money-backed probability estimate. For context, that model has historically sat in a gray zone in the United States, where the Commodity Futures Trading Commission oversees event contracts and regulators have spent years debating how close a wager on an election sits to a wager at a casino. The business already lives one bad headline away from a policy problem. Add an investor tied to the president's family, and the headline risk picks up a political multiplier.
That is why the DealBook stage matters. The summit is where executives go to shape a narrative in front of the exact audience that amplifies it: investors, journalists, and the policymakers who watch the clips. Coplan's choice to address the Trump Jr. link directly, rather than let it harden into an unanswered question, follows a standard playbook. Naming a criticism and calling it overblown is cheaper than refusing to discuss it, and it puts the company's own framing on the record first.
The substance behind the spin is a two-audience problem. Audience one is Washington. A prediction market whose core output is political probability, financed in part by a firm associated with the president's oldest son, invites questions about optics even when nothing improper occurs, and optics is often what regulators respond to. Audience two is institutional. Exchanges, brokers, media partners, and the large trading firms that might bring liquidity all run reputational math before they sign. Every one of those counterparties has to ask whether a Trump-family-adjacent backer is an asset, a liability, or a footnote.
Coplan's bet is the footnote. Calling the involvement overblown is an argument that money is money, that the investor's firm is one line on a longer cap table, and that the market's users care about liquidity and accuracy, not ownership. That argument has real support in how markets usually work: capital is capital, and prediction markets have always drawn a mixed crowd of quants, speculators, and political obsessives. But it also skips a step. The value of a prediction market is not just the price it prints; it is the credibility of that price.
Credibility is the scarce asset here, and it is fragile. If the public concludes that a market pricing political outcomes is wired to political power, the probability estimates stop being useful as a neutral signal, and the platform loses the one thing that separates it from a sportsbook. That is the second-order risk Coplan is managing with a single word. He is not really defending an investor. He is defending the idea that Polymarket's numbers mean something independent of who owns a piece of the company.
For founders and boards watching, the lesson is not that political money is toxic, nor that it is a shortcut. It is that politically connected capital arrives with a disclosure and governance bill attached, and that bill comes due in public. The cost is not the check; it is the years of explaining. Companies that take it on should decide in advance who speaks for the cap table, what gets disclosed and when, and how they answer the conflict question before a reporter asks it at a summit.
Coplan answered it his way: overblown. The follow-up is the one that matters. If Polymarket keeps growing, expanding into new markets, and courting mainstream partners, the Trump Jr. connection will be tested by events rather than adjectives. The next regulatory decision, the next big liquidity partner, the next election cycle will each re-ask the question. Founders can call a story overblown. They cannot call it over.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business

S&P 500 Enters Correction, Down 10% From Its High on AI Worries
The index's slide past the 10 percent line is a symbolic verdict on investor mood, and the AI trade that powered the rally is now the thing testing it.

Dow and S&P 500 enter correction as Nasdaq logs worst week since 2020
All 11 S&P 500 sectors fell more than 1% in the same week for the first time since April 2025, a breadth signal that matters more than any single index level.

Chip stocks lose $2.3 trillion in a week, worst run in 25 years
A $2.3 trillion weekly wipeout in semiconductors is forcing every board with an AI story to ask whether it owns a thesis or just a crowded trade.