
Tesla will sell you a $29,900 Cybercab, then bill $299 a month
Tesla's limited Cybercab release puts a two-seat, pedal-free car in private hands by December, but owners inherit a $299 monthly fee, drive restrictions, and a resale block.
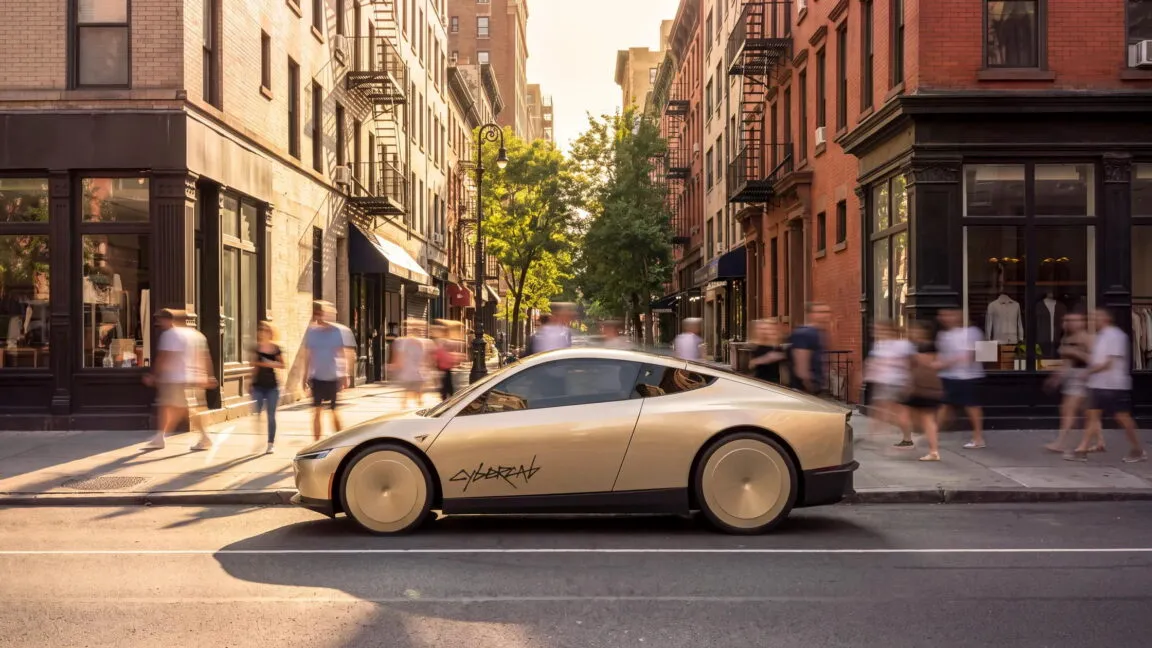
Tesla invited "select customers" last Friday night to buy its two-seat, steering-wheel-free Cybercab for $29,900 with December delivery, attached to a $299 monthly charge and contractual limits on where the car drives and whether it can be resold. The offer reframes autonomous vehicles as a controlled subscription rather than a clean sale, resetting expectations for residual values, fleet economics, and every rival weighing whether to sell robotaxis or keep them.
Tesla put a number on the Cybercab last Friday night, and the number is not the whole number. The company said it had invited "select customers" to purchase the two-seat, gold, steering-wheel-free vehicle for $29,900, with delivery slated for December. Tesla called it a "limited release" and did not say how many people received the invitation. What comes with the car is a recurring $299 monthly charge, the catch flagged in Ars Technica's headline, plus a set of controls that let Tesla decide where the vehicle drives and whether its owner can sell it. There is always a catch. Here there are several, and they are the interesting part.
Start with the leash. Tesla can restrict where Cybercabs drive and can block owners from reselling them, according to the report. Sit with that for a second: a $29,900 asset you cannot freely sell. Resale value is the quiet engine of car ownership economics. It sets lease residuals, it sets collateral values for lenders, and it determines how fast a buyer can get out if life changes. Cut that off and the Cybercab stops behaving like a car and starts behaving like a license. The monthly fee compounds the point. The Cybercab "will need constant cash infusions to stay on the road," and $299 a month works out to $3,588 a year on top of the purchase price. This is a hardware sale bolted to a software relationship that Tesla controls and Tesla bills.
The contrast that makes the strategy legible: Alphabet's Waymo and Amazon's Zoox both run self-driving ride-hail networks, and neither lets customers buy the cars. They keep the fleet, the software and the margin in one place and sell rides. Tesla is doing the reverse. It sells the hardware and keeps the strings. That is the actual bet here, and it is a bet about who carries the risk. Under the Waymo model, the company eats the depreciation, the downtime and the regulatory exposure, and charges for usage. Under Tesla's model, the buyer eats the $29,900, and Tesla still gets a monthly check, visibility into where the car goes, and a veto on who owns it next.
For buyers, the arithmetic is less friendly than the sticker suggests. A $29,900 purchase price is a mass-market number. A $29,900 purchase price plus $3,588 a year in perpetuity is not. Compare that to what a conventional car costs to own and the framing shifts: the Cybercab's headline price buys the hardware, and the subscription buys the right to keep using it. Owners are effectively prepaying for a service whose terms Tesla writes, and whose scope Tesla can narrow. If Tesla can restrict where the car drives, it can, at least in principle, shrink the usable value of the asset after the money has changed hands.
Context matters on the technical side, too. A vehicle with no steering wheel and no brake pedals sits awkwardly against safety rules written on the assumption that a human is holding something. Historically, US federal motor vehicle safety standards have been built around driver controls, which is why companies pushing vehicles without them have typically had to engage regulators early and carefully rather than simply ship. Tesla's "limited release" framing fits that pattern: a small, hand-picked cohort, a December delivery window, and no disclosed volume. That is not a product launch so much as a controlled experiment with paying participants.
What Tesla gets from the arrangement is considerable. It collects $29,900 up front and a recurring fee after that, without owning the fleet, the depots or the labor. It gets real-world driving data from cars in private hands. It keeps a veto over resale, which means it can shape the secondary market instead of watching it form. And it retains the ability to restrict operating areas, which is a useful dial if regulators, insurers or city governments push back in specific places. Every one of those levers is a lever a normal car buyer would never grant an automaker.
What remains unanswered is nearly as telling as what was announced. Tesla did not say how many customers were invited. It did not publish the full terms behind the $299 monthly charge, or specify what happens to that fee if the software is not ready on schedule, or define precisely what "restricting where Cybercabs drive" means in practice. Those gaps are where the real contract lives, and any buyer, lender or insurer underwriting a Cybercab needs them closed before signing.
The strategic stakes reach past Tesla. Every automaker working on autonomy now faces the same fork: sell the vehicle and keep the software, or keep both and sell the ride. Tesla just showed the market a third path, one where the customer buys the hardware, funds the software monthly, and accepts limits on where the asset can go and who can own it next. Rivals will be asked why they are not doing the same. Boards should be ready with an answer, because the $29,900 on the sticker is the least interesting number in this deal.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business

S&P 500 Enters Correction, Down 10% From Its High on AI Worries
The index's slide past the 10 percent line is a symbolic verdict on investor mood, and the AI trade that powered the rally is now the thing testing it.

Dow and S&P 500 enter correction as Nasdaq logs worst week since 2020
All 11 S&P 500 sectors fell more than 1% in the same week for the first time since April 2025, a breadth signal that matters more than any single index level.

Chip stocks lose $2.3 trillion in a week, worst run in 25 years
A $2.3 trillion weekly wipeout in semiconductors is forcing every board with an AI story to ask whether it owns a thesis or just a crowded trade.