
Anthropic's I.P.O. Made Rank-and-File Researchers Worth Tens of Millions
Researchers who joined just a few years ago are now worth tens of millions, and the windfall resets the pay benchmark for every private A.I. lab still paying in paper.

Anthropic's I.P.O. has turned many early employees, including researchers who joined only a few years ago, into holders of tens of millions of dollars, according to The New York Times. The windfall resets compensation benchmarks across private A.I. labs, where equity rather than salary is the primary weapon in the fight for scarce research talent.
Anthropic's I.P.O. has quietly minted a new class of millionaires, and the striking part is who they are. According to The New York Times, many people who joined the A.I. company a few years ago, with little reason to believe it would become as big as it has, are now worth tens of millions of dollars, if not more. These are not founders cashing out a life's work. They are researchers and early employees whose pay leaned heavily on equity that, at the time they signed, looked like a long shot.
The math behind that outcome is worth sitting with, because it is now the standard pitch across the A.I. industry. A researcher who joins a private lab typically accepts a salary below what a large public tech company would pay and takes the difference in options or restricted stock. The strike price is set when the business is valued at a fraction of its eventual worth. When the company lists shares, that paper becomes liquid, and the gap between the two valuations lands in the employee's account. For a meaningful grant, the difference is not a nice bonus. It is a net worth in the tens of millions, which is precisely the position the Times describes for many of these employees.
The timing is rarely as instant as the phrase "overnight millionaire" suggests. Equity at a newly public company typically vests over four years with a one-year cliff, and employees are usually locked out of selling for a set period after listing, commonly around six months. Exercising options can also require real cash up front, and the tax bill on a windfall of that size is a separate problem. For context, the difference between incentive stock options and non-qualified options can swing a tax bill by millions, which is why wealth managers tend to appear the moment a company files to go public. The wealth is real, but it arrives on a schedule.
Why does this happen at an A.I. lab rather than, say, a logistics startup? Because in frontier A.I., the scarce input is not capital or compute. It is people who can train and fine-tune large models, and there are not many of them. Labs compete for the same short list of researchers, and the currency of that competition is equity. Anthropic sits in that market alongside the other best-funded labs, which means its recruiting pitch has always been part of its cost structure. The I.P.O. did not create the strategy. It just converted the promises into prices.
The awkward part for Anthropic and its peers: liquidity cuts both ways. Equity is a retention tool precisely because it is illiquid. Once employees can sell, the golden handcuffs loosen, and the people who just became wealthy have the least financial reason to stay through the next hard push. Companies typically respond with fresh grants, retention packages, or longer vesting schedules, all of which show up as new dilution. Boards should expect that conversation. It is the direct cost of a successful listing.
The wider signal matters beyond one company. Every private A.I. lab now has a reference point for what its own employees are worth on paper, and a workforce that has watched a competitor's staff get liquid. That typically pushes private companies toward tender offers, secondary sales, or their own path to the public markets, because the alternative is watching engineers leave for a place that pays in cash. The reverse is also true. If the shares fall after the lockup expires, the recruiting pitch weakens and the paper millionaires become a cautionary story instead of a sales pitch.
There is also a cultural bill that does not show up on a balance sheet. A company where a 28-year-old researcher is worth tens of millions and a mid-level operator two desks over is not can develop two very different relationships to risk, to overtime, and to staying. That is a management problem, not a finance one, and it tends to surface after the lockup lifts rather than before.
For executives and boards, the lesson is that a public listing is a compensation event, not just a financing event. It resets the benchmark for every engineer in the market, it creates internal wealth gaps that can reshape culture, and it hands your best people the freedom to walk. For anyone weighing a job at a private A.I. company, the reverse also applies: equity is now a priced-in part of the offer, so it deserves to be negotiated like cash, with the same scrutiny on strike price, vesting, and what happens if the company never lists. Anthropic's researchers got the outcome everyone hopes for. Most people who take the same bet do not, and the ones who do should know exactly what they are holding before the lockup lifts.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Science

Sea Lion Culling Strategy Fails: New Model Says Killing Them Won't Save Salmon
The latest research from AAAS overturn a long-held conservation assumption, forcing policymakers to rethink critical resource allocation in marine ecosystems.
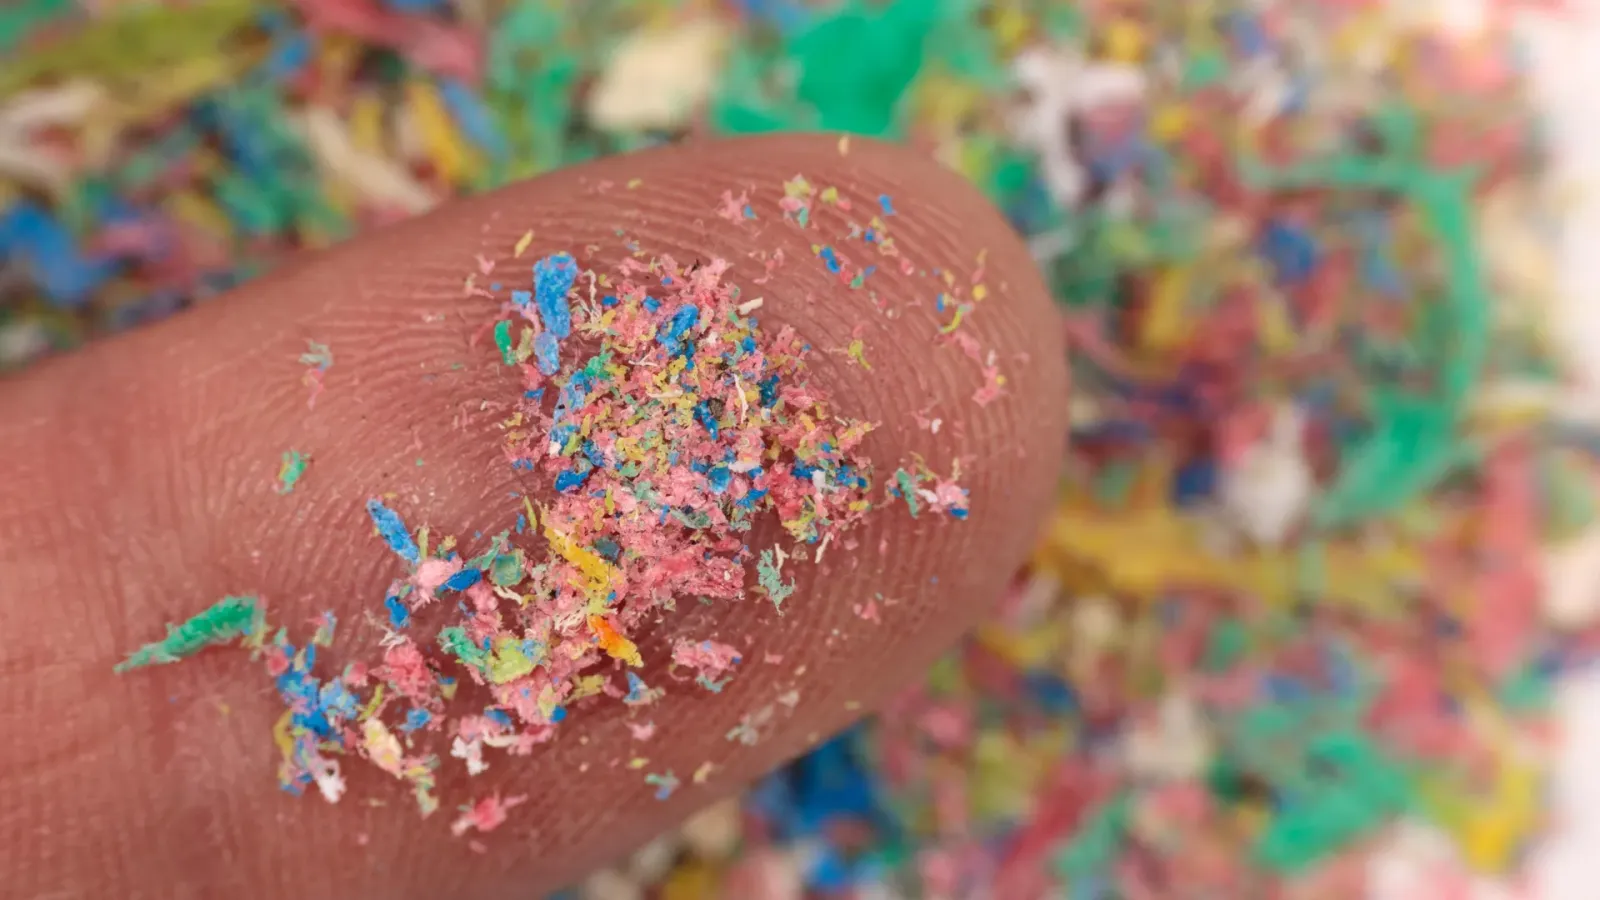
Microplastics do more than pile up: they react with water to damage cells
Scientists have found that plastic particles can generate highly reactive molecules in water, a mechanism that could explain links to heart attacks, strokes, and neurological disorders.
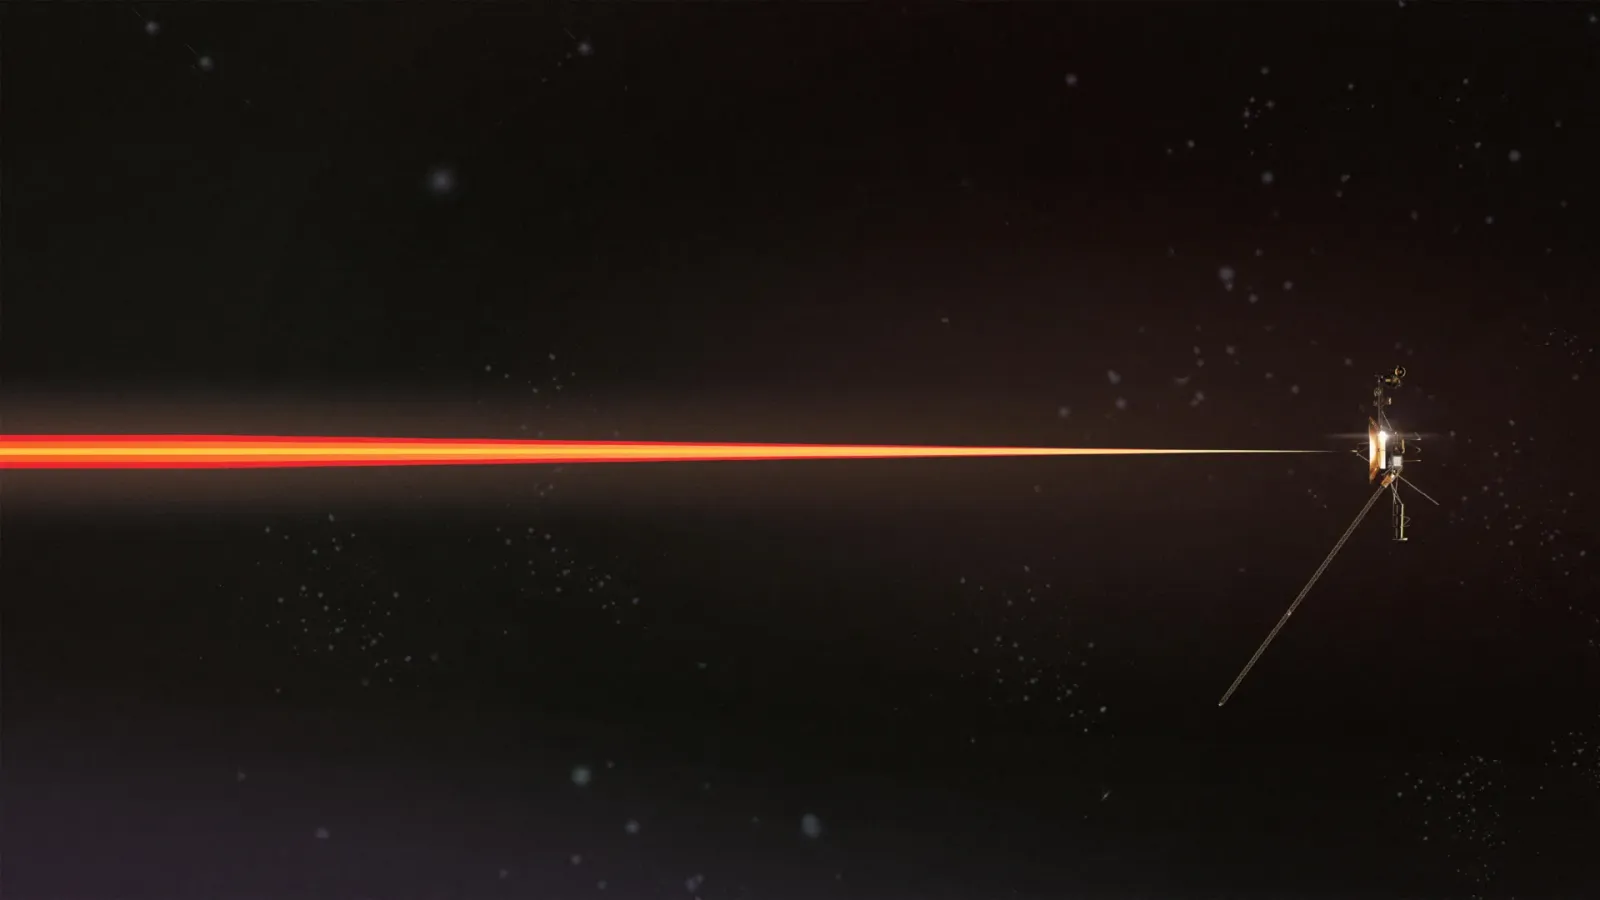
Voyager 1 is a full day from Earth, and its power is running out
The 1977 probe is 16.1 billion miles out, the first human object whose radio calls take 24 hours to arrive, and its shrinking power supply is the real deadline.